Q-Line Biotech NSE SME IPO review

  • The company is engaged in the business of developing, manufacturing and marketing of diverse range of reagents and consumables.
  • It posted growth in its top lines for the reported periods, but suffered a setback for FY25 in bottom line following accounting adjustments.
  • As the company has no listed peers, it is trying to extract fancy price for its IPO.
  • Based on its overall financial data, the issue appears fully priced.
  • Well-informed investors may park moderate funds for long term.
Dilip Davda

About Company

Q-Line Biotech Ltd. (QBL) is engaged in the business of developing, manufacturing and marketing of diverse range of reagents (including kits and POC devices) & consumables and manufacturing, importing, distribution/supply of diagnostic equipment for different diagnostic healthcare needs. The company supplies diagnostic equipment and IVD products for different diagnostic healthcare needs since 2013 directly or through its distributor/s majorly to diagnostic service providers, hospitals and medical colleges. 

The company has established its brands over a period of 12 years through its experience, R & D, manufacturing capabilities and quality assurance. The core segments of operations of the Company in IVD Industry include Clinical Chemistry, Haematology, Immunodiagnostics, Molecular Diagnostics and Others (POC Devices & Rapids).

QBL’s key manufacturing segments include indigenous manufacturing of reagents including Clinical Chemistry, Haematology, Immunodiagnostics, Molecular Diagnostics and Others (POC Devices & Rapids) and supplying/ manufacturing of in-vitro diagnostics (IVD), Pathology equipment’s & devices. Further during the Covid-19 pandemic, the company diversified its focus and with the technical collaboration of third-party institutes and through its own R&D team developed a range of Covid testing kits viz. RT-PCR Kits, RNA Extraction Kits, VTM Kits etc.

It is research driven company engaged in developing and manufacturing a wide range of reagents formulations used across various IVD and diagnostic needs. The company leverages its R&D capabilities to develop and manufacture a portfolio of differentiated reagent formulations /products. Further, for its certain Class of Reagent & equipment’s and devices manufacturing business, the company has entered into technical collaboration with certain international companies. Under the agreement terms, it undertakes the manufacturing of these Reagent and equipment’s and devices as per the technical collaboration and specifications provided by the partners or companies. 

With the help of these collaborations the equipment and devices adhere to strict quality control, international standards and certifications. As of March 31, 2026, the company employed 19 personnel at R&D laboratories, which constituted 5.25% of its total permanent employee strength. As of March 31, 2026, it had 362 employees on its payroll and additional 223 contract employees in various departments.

Q-Line Biotech IPO

Issue Details / Capital History

The company is coming out with its maiden book building route IPO of 6253200 equity shares of Rs. 10 each to mobilize Rs. 214.48 cr. at the upper cap. The company has announced a price band of Rs. 326 - Rs. 343 per share.  The minimum application to be made is for 800 shares and in multiples of 400 shares thereon, thereafter. The IPO opens for subscription on May 21, 2026, and will close on May 25, 2026. The IPO constitute 26.81% of the post-IPO paid-up capital of the company. The shares will be listed on NSE SME Emerge. From the net proceeds of the IPO, it will utilize Rs. 93.50 cr. for working capital, Rs. 90.00 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes. 

The company raised Rs. 27.44 cr. in a pre-IPO placement of 800000 shares in May 2026, at Rs. 343 per share.

The IPO is jointly lead managed by Hem Securities Ltd., and Share India Capital Services Pvt. Ltd., Purva Sharegistry (India) Pvt. Ltd., is the registrar to the issue. HEM group’s Hem Finlease Pvt. Ltd., is the market maker as well as a syndicate member.

The company has issued initial equity capital at par value. It raised further equity shares in the price range of Rs. 125 – Rs. 417 between March 2019 and May 2026. It has also issued bonus shares in the ratio of 2 for 1 in March 2016, and 9 for 1 in August 2025. The average cost of acquisition of shares by the promoters is Rs. 0.00, Rs. 0.04, and Rs. 18.34 per share.

Post-IPO, company’s current paid-up equity capital of Rs. 17.07 cr. will stand enhanced to Rs. 23.33 cr. Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 800.16 cr. 

IPO Lead Managers & Registrar

Financial Performance

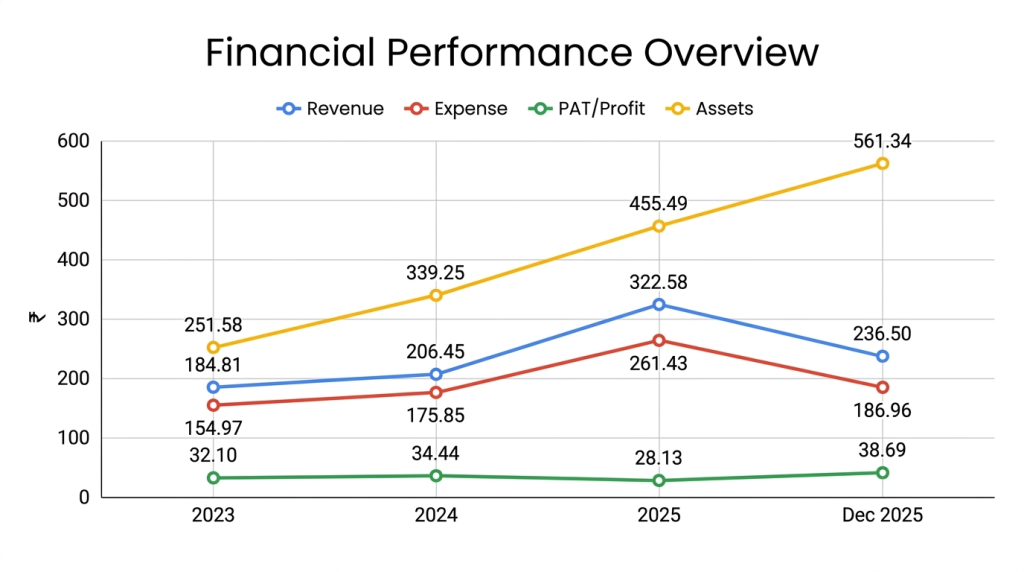
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted total income/ net profit, of Rs. 184.81 cr. / Rs. 32.10 cr. (FY23), Rs. 206.45 cr. / Rs. 34.44 cr. (FY24), Rs. 322.58 cr. / Rs. 28.13 cr. (FY25). For 9M of FY26 ended on December 31, 2025, it earned a net profit of Rs. 38.69 cr. on a total income of Rs. 236.50 cr. Though it posted growth in its top lines for the reported periods, its bottom line posted inconsistency. For FY25, it posted lower net profit of Rs. 28.13 cr., and for 9M-FY26, though the top line is Rs, 236.50 cr. it posted bumper profit of Rs. 38.69 cr. in a pre-IPO period, that not only raise eyebrows, but also concern over its sustainability going forward. Despite higher other income for FY25, it marked lower net following extra-ordinary item of Rs. 16.97 cr. Its contingent liability stood at Rs. 61.64 cr. as of December 31, 2025, that raises alarm. Its overall borrowings of Rs. 242.57 cr. as of December 31, 2025, raise concern.

For the last two fiscals, the company has reported an average EPS of Rs. 25.00, and an average RoNW of 23.17%. The issue is priced at a P/BV of 2.44 based on its NAV of Rs. 140.81 per share as of December 31, 2025, but its post-IPO NAV data is missing from the offer documents.

If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 15.51, and based on FY25 earnings, the P/E stands at 28.44. The issue appears fully priced, based on its bumper earnings for 9M-FY26, which may not be sustained. 

For the reported periods, the company has posted PAT margins of 17.56% (FY23), 16.92% (FY24), 8.97% (FY25), 16.65% (9M-FY26), and RoCE margins of 22.14%, 19.25%, 17.66%, 13.32%, respectively, for referred periods.

All amounts in Indian Rupees crores

Period Ended Revenue Expense PAT Assets
2023 ₹184.81 ₹154.97 ₹32.10 ₹251.58
2024 ₹206.45 ₹175.85 ₹34.44 ₹339.25
2025 ₹322.58 ₹261.43 ₹28.13 ₹455.49
Dec 2025 ₹236.50 ₹186.96 ₹38.69 ₹561.34

Dividend Policy

The company has not paid any dividends for the reported periods of the offer document. It will adopt a prudent dividend policy, based on its financial performance and future prospects. 

Comparison with Listed Peers - for Fiscal 2025

As per the offer document, the company has no listed peers to compare with.

Name of the Company Face Value (₹) EPS basic (₹)Ā  EPS Diluted (₹) RONW (%) P/E Ratio NAV (₹)
Powerica Limited 5 15.26Ā  15.26 15.37 %Ā  24.45 99.76
Listed Peers
Cummins India Limited 2 72.15Ā  72.15 26.45% 64.13Ā  272.78
Kirloskar Oil Engines Limited 2 33.71 33.60 15.85% 43.24 212.60
NTPC Green Energy Limited 10 0.67 0.67 2.58% 129.40 21.88
Acme Solar Holdings Limited 2 4.55 4.53 5.59% 50.74Ā  74.54
Adani Green Energy Limited 10 8.37 8.37 11.90%Ā  101.53Ā  76.62
Disclaimer: Above table shows earnings and P/E ratio as of 2025-26

Merchant Banker's Track Record

The two merchant bankers associated with this issue have handled 79 issues in the past three years, out of which 8 issues closed below the issue price on listing date.

Conclusion - Apply for medium to long term

QBL is engaged in the business of developing, manufacturing and marketing of diverse range of reagents and consumables. It posted growth in its top lines for the reported periods, but suffered a setback for FY25 in bottom line following accounting adjustments. As the company has no listed peers, it is trying to extract fancy price for its IPO. Based on its overall financial data, the issue appears fully priced. Well-informed investors may park moderate funds for long term.

Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.

He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.

Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.

FAQ Accordion
Q-Line Biotech IPO FAQs
1. What is Q-Line Biotech IPO? āŒ„
Q-Line Biotech IPO is SME IPO. The company is going to raise ₹214 Crores via IPO. The issue is priced at ₹326 to ₹343 per equity share. The IPO is to be listed on NSE SME.
2. When Q-Line Biotech IPO will open for subscription? āŒ„
The IPO is to open on May 21, 2026 for QIB, NII, and Retail Investors. The IPO will close on May 25,2026.
3. What is Q-Line Biotech IPO Investors Portion? āŒ„
The investors’ portion for QIB is 50%, NII is 15%, and Retail is 35%.
4. How to Apply the Q-Line Biotech IPO? āŒ„
You can apply for Q-Line Biotech IPO via ASBA online via your bank account. You can also apply for ASBA online via UPI through your stock brokers. You can also apply via your stock brokers by filling up the offline form.
5. What is Q-Line Biotech IPO Issue Size? āŒ„
Q-Line Biotech IPO issue size is ₹214 crores.
6. What is Q-Line Biotech IPO Price Band? āŒ„
Q-Line Biotech IPO Price Band is ₹326 to ₹343.
7. What is Q-Line Biotech IPO Lot Size? āŒ„
The minimum bid is 800 Shares with ₹2,74,400 amount.
8. What is the Q-Line Biotech IPO Allotment Date? āŒ„
Q-Line Biotech IPO allotment date is May 26,2026.
9. What is the Q-Line Biotech IPO Listing Date? āŒ„
Q-Line Biotech IPO listing date is May 29, 2026. The IPO is to list on NSE SME.

Paramount Syntex IPO 2026: Strong Financial Momentum, Synthetic Fibre Opportunity and Growth Plans

Paramount Syntex IPO is set to open on September 30, 2026, with the company offering its shares in the price band of ₹119 to ₹127. The BSE SME-bound issue comes at an interesting stage in the company’s journey: revenue has expanded, profitability has accelerated sharply, and a substantial portion of the IPO proceeds is earmarked for machinery at the existing manufacturing facilities.

For investors tracking emerging textile manufacturers, the combination of an integrated operating platform, stronger FY26 earnings and a clearly defined capital-expenditure plan makes Paramount Syntex an issue worth watching closely.
Paramount Syntex IPO

Paramount Syntex IPO 2026 – Key Details

ParameterDetails
IPO Open Date30 September 2026
IPO Close Date6 October 2026
Price Band₹119 to ₹127 per share
Face Value₹10
Market Lot1,000 shares
Minimum Application2,000 shares
Minimum Amount at ₹127₹2,54,000
Issue SizeApprox. ₹82 crore
Net Issue61.17 lakh shares
Market Maker Portion3.23 lakh shares
ListingBSE SME
Allotment7 October 2026
Tentative Listing Date9 October 2026

Paramount Syntex: A Business Built Around Synthetic Fibres and Yarns

Founded in 1996, Paramount Syntex manufactures synthetic fibres, dyed fibres and multiple yarn categories including acrylic, polyester, wool, nylon and blended yarns. The company’s manufacturing process covers fibre processing, tow dyeing, hank dyeing, spinning, bulking and packing, giving it an integrated presence across several stages of production. It also manufactures recycled acrylic fibre from waste materials, adding a sustainability-oriented product line to its portfolio.

Integrated Manufacturing Can Support Product Flexibility

The integrated manufacturing model is one of the key features of Paramount Syntex. In-house processing across multiple stages can provide greater control over product specifications, quality and production scheduling. With textile customers increasingly seeking differentiated fibres and yarns, the ability to process and supply multiple product categories can support broader market participation.

The Financial Acceleration Is the Key Highlight

Paramount Syntex has shown a significant improvement in earnings over the last three financial years. Revenue increased from ₹92.94 crore in FY24 to ₹112.72 crore in FY25 and ₹122.51 crore in FY26. More importantly, profitability expanded at a much faster pace. PAT increased from ₹1.35 crore in FY24 to ₹6.73 crore in FY25 and ₹13.87 crore in FY26.

MetricFY24FY25FY26
Revenue / Total Income₹92.94 cr₹112.72 cr₹122.51 cr
EBITDA₹9.66 cr₹13.56 cr₹24.21 cr
PAT₹1.35 cr₹6.73 cr₹13.87 cr
EPS——₹11.60

FY26 PAT growth was approximately 106% over FY25, while FY26 EBITDA reached ₹24.21 crore. The reported FY26 ROE of 32.50%, ROCE of 29.18% and EBITDA margin of 19.33% provide additional context on the company’s improved operating profile. The key question for the post-IPO phase will be whether this stronger profitability can be sustained as capacity and machinery investment progress.

₹61.68 Crore Machinery Investment: A Major Growth Lever

According to IPOWatch’s current issue details, ₹61.68 crore of the IPO proceeds is earmarked for capital expenditure toward machinery at the existing facilities. This gives the issue a clear operating purpose rather than being primarily a liquidity event for existing shareholders. Successful deployment of the machinery could strengthen production capability, efficiency and the company’s ability to serve growing demand.

A Favourable Positioning Within the Synthetic Fibre Value Chain

India’s man-made fibre and textile ecosystem continues to receive policy support, while manufacturers are investing in capacity, product development and value-added processing. Paramount Syntex’s presence across synthetic fibres and yarns places the company within a segment where scale, quality, processing capability and product diversity can influence competitive positioning.

Paramount Syntex IPO Valuation

At the upper price band of ₹127, the reported FY26 EPS of ₹11.60 translates into an offer-price-to-FY26-EPS multiple of approximately 10.9x. The company also reports a FY26 NAV of ₹35.68 per share. The valuation needs to be considered alongside the company’s recent earnings acceleration, planned machinery investment, SME-market structure and the sustainability of future margins.

Paramount Syntex IPO HNI / NII Application Details

The SME IPO structure creates a meaningful application size. At ₹127, the minimum application of 2,000 shares requires ₹2.54 lakh. The S-HNI minimum is 3,000 shares, requiring ₹3.81 lakh, while the B-HNI minimum is 8,000 shares, requiring ₹10.16 lakh. These larger ticket sizes make the issue particularly relevant to investors who routinely participate in SME IPOs through the NII/HNI category.

Promoter Holding Adds Long-Term Alignment

IPOWatch reports promoter and promoter-group ownership of 91.74% before the issue and 59.63% after the issue. The substantial post-issue promoter holding indicates that the existing promoters continue to retain a significant stake following the IPO.

Key Factors That Could Drive the Next Phase

  • Strong FY24–FY26 improvement in PAT and EBITDA
  • ₹61.68 crore earmarked for machinery and capital expenditure
  • Integrated manufacturing across fibres, dyeing, spinning and yarn processing
  • Exposure to synthetic fibres, blended yarns and recycled acrylic fibre
  • Potential for higher operating scale and better utilization of the manufacturing platform
  • Policy and demand support for India’s man-made fibre and textile ecosystem
  • Meaningful promoter ownership after the IPO

Risks Investors Should Track

  • Raw-material and energy-cost volatility can affect textile manufacturing margins
  • Textile demand can be cyclical and sensitive to economic conditions
  • Customer concentration and product mix can influence revenue visibility
  • Capex benefits depend on timely installation and effective utilization of machinery
  • Working-capital requirements can increase as the business scales
  • SME-listed shares can experience lower liquidity and wider price movements than mainboard stocks

Paramount Syntex IPO Timeline

EventDate
IPO Opens30 September 2026
IPO Closes6 October 2026
Basis of Allotment7 October 2026
Refund / Demat Credit8 October 2026
Tentative Listing9 October 2026

Paramount Syntex IPO Review

Paramount Syntex comes to the SME market with several measurable developments already visible in its financial statements. The company has moved from ₹1.35 crore of PAT in FY24 to ₹13.87 crore in FY26, while EBITDA has expanded to ₹24.21 crore. At the same time, the IPO provides capital specifically for machinery, creating a defined pathway for strengthening the existing manufacturing platform.

The combination of improving earnings, integrated synthetic-fibre operations, a substantial machinery programme and continued participation in the growing man-made fibre value chain gives the company several identifiable operating triggers for the coming years. The outcome will ultimately depend on demand, margins, execution and capital efficiency, but the current numbers provide a substantially stronger earnings base from which the company enters its listed journey.

Disclaimer

This article is promotional content. Investors are advised to make their own decisions and apply entirely at their own risk. This article is written using information from the company’s RHP (Red Herring Prospectus) data and online sources. Readers should conduct their own research and due diligence before making any financial decision. If you have any queries, kindly contact the IPO Watch Team.

Paramount Syntex IPO FAQs

When does Paramount Syntex IPO open?

Paramount Syntex IPO is open on September 30, 2026.

When does Paramount Syntex IPO close?

Paramount Syntex IPO is close on October 6, 2026.

What is the Paramount Syntex IPO price band?

Paramount Syntex IPO Price Band is ₹119 to ₹127 per share.

What is the Paramount Syntex IPO lot size?

The Paramount Syntex IPO lot size is 1,000 shares, with a minimum application of 2,000 shares.

What is the minimum investment?

The minimum investment of Paramount Syntex IPO is set as ₹2.54 lakh at the upper price band.

What is the Paramount Syntex IPO HNI investment?

The HNI investment of Paramount Syntex IPO is set as S-HNI starts at ₹3.81 lakh and B-HNI starts at ₹10.16 lakh at the upper price band.

Where will Paramount Syntex IPO list?

The Paramount Syntex IPO will be listed on BSE SME, with tentative listing on 9 October 2026.

How much IPO money is earmarked for machinery?

According to the current IPOWatch issue details, ₹61.68 crore IPO money is earmarked for machinery.

What was Paramount Syntex PAT in FY26?

The Paramount Syntex PAT in FY26 is ₹13.87 crore.

What is Paramount Syntex FY26 EPS?

The Paramount Syntex FY26 EPS is ₹11.60.


Picture of Jagat Joshi

Jagat Joshi

Founder of IPOWatch, brings nearly 15 years of experience in IPO analysis and market research. He provides complete coverage of upcoming IPOs, subscription trends, grey market premiums (GMP), and post-listing performance, along with easy-to-understand reviews, insights, and analysis. In his working journey, he has worked with various platforms and received expertise in stock market analysis and primary markets.
Picture of Jagat Joshi

Jagat Joshi

Leave a Reply

Your email address will not be published. Required fields are marked *

Current SME IPO

Join WhatsApp Channel