Hero Motors IPO Review – Only Well-Informed/Cash Surplus Investors May Park Moderate Funds for Medium to Long Term
Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO worth Rs. 1000 cr. (of approx. 119047619 equity shares at the upper cap). The IPO consists of fresh equity shares worth Rs. 600 cr. (approx. 71428571 equity shares at the upper cap) and an Offer for Sale (OFS) worth Rs. 400 cr. (approx. 47619048 equity shares at the upper cap). The company has announced a price band of Rs. 79 – Rs. 84 per equity shares of Rs. 10 each. The issue opens for subscription on September 16, 2026, and will close on September 18, 2026. The minimum application to be made is for 178 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 26.21% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 200.00 cr. for capex towards purchase of equipments needed for expansion, Rs. 190.00 cr. for repayment/prepayment of certain borrowings, and the rest for inorganic growth through unidentified acquisitions / general corporate purposes.
The three joint Book Running Lead Managers (BRLMs) to this issue ICICI Securities Ltd., DAM Capital Advisors Ltd., JM Financial Ltd., while KFin Technologies Ltd. is the registrar to the issue. Sharekhan Ltd., and JM Financial Services Ltd. are the syndicate members.
After issuing entire equity shares at par value, the company has issued/converted further equity shares in the price range of Rs. 62 – Rs. 69.14, between September 2007, and September 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 0.03, Rs. 0.04, and Rs. 10.07 per share.
Post-IPO, its current paid-up equity capital of Rs. 382.79 cr. (382787005 equity shares) will stand enhanced to Rs. 454.22 cr. (454215576 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 3815.41 cr.
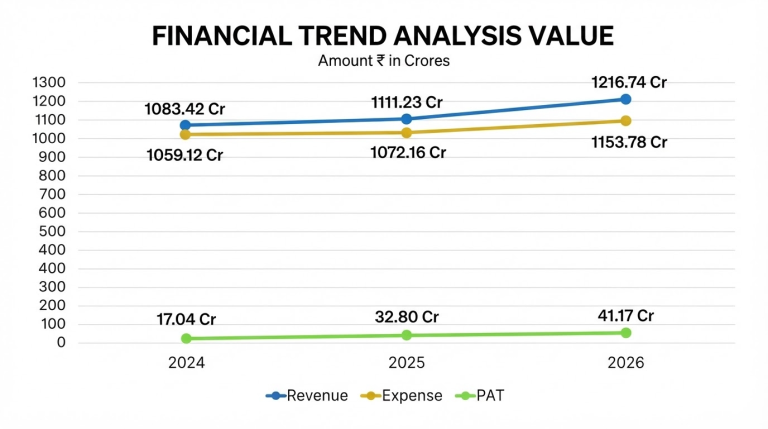
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit, of Rs. 1083.42 cr. / Rs. 17.04 cr. (FY24), Rs. 1111.23 cr. / Rs. 32.80 cr. (FY25), and Rs. 1216.74 cr. / Rs. 41.17 cr. (FY26). Thus, it marked steady growth in its top and bottom lines for the reported periods. Its contingent liabilities stood at Rs. 24.42 cr. as of March 31, 2026.
For the last three fiscals, the company has posted an average EPS of Rs. 0.86 (basic) and an average RoNW of 7.58 %. The issue is priced at a P/BV of 6.60 based on its NAV of Rs. 12.72 as of March 31, 2026, and at a P/BV of 3.52 based on its post-IPO NAV of Rs. 23.83 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 92.31. Based on FY25 earnings, the P/E stands at 116.67. The issue appears exorbitantly priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 1.60% (FY24), 3.01% (FY25), 3.46% (FY26), and RoCE margins of 23.23%, 18.84%, 19.77%, respectively, for the referred periods.
All amounts in Indian Rupees crores
The company has paid a dividend of 2.50% for FY24, FY25, and 3.20% for FY27, till filing of this offer document. It has already adopted a dividend policy in August 2024, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown CIE Automotive, Endurance Techno, Sona BLW, Uno Minda, Varroc Engg., as its listed peers. They are currently trading at a P/E of 16.1, 38.5, 63.3, 56.8, and 46.7 (as of September 11, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Hero Motors Ltd. (HML) is one of India’s leading solutions providers to global e-mobility industry (Source: CRISIL Report) with its revenue from sales to e-mobility industry being Rs. 273.29 cr., Rs. 175.59 cr. and Rs. 128.09 cr., accounting for 23.00%, 16.12% and 12.03%, respectively of its revenue from operations for Fiscal 2026, 2025 and 2024, respectively. It is among the few companies globally that design high-performance transmission systems capable of handling tough torque needs while keeping components lightweight and meeting noise, vibration and harshness (“NVH”) requirements of electric vehicles. The company is a part of HMC group.
Over the last five years, it has expanded market presence across automotive segments and has grown its business with premium two-wheeler OEMs globally. In the premium two-wheeler segment, it has partnered with OEMs such as BMW, Ducati and a leading American two-wheeler OEM among others, for Powertrain Solutions covering design, development, prototyping, validation and high-volume manufacturing. The global e-bike market is projected to reach 12.5 million to 14.5 million units by 2031 at a CAGR of 6% to 9% (from 2024 to 2031). E-bike sales in Europe are expected to grow at a CAGR of 5% to 8%, reaching 8 to 10 million units by 2031, while the U.S. market are expected to grow at a CAGR of 16% to 19%.
The global two-wheeler industry is expected to witness a significant acceleration in electrification through 2031, with electric motorcycles and scooters gaining share across major markets. EV penetration in the motorcycle segment is projected to increase from 2.0% in 2025 to 10.5% to 12.5% by 2031, reflecting a robust CAGR of 34% to 38%, supported by improving battery technology, expanding charging infrastructure, and growing government support for electric mobility. Advancements in battery technology and design have made e-bikes a serious contender for commuting, recreation and utility cycling. (Source: CRISIL Report)
The contribution of e-mobility to its sales accounted for 23.00% of revenue from operations in Fiscal 2026. Longstanding Relationships with Premier Global Original Equipment Manufacturers and Expertise in Delivering Solutions, it has a diverse and premium customer base, serving clients both in India and internationally. In the automotive sector, HML collaborated with global two-wheeler OEMs including BMW, Ducati, and Hero MotoCorp; players from motor sport industries such as Formula Motorsport and HWA Engineering; global commercial vehicle and off-road OEMs such as Escorts; and enviolo. Its customers in the non-automotive segment for both electric and non-electric powertrain and transmission systems include global OEMs such as B&S, and various e-powertrain applications for supercar manufacturers. As of March 31, 2026, it had 1388 employees on its payroll, and additional 707 contract labour in various departments.
Merchant Banker's Track Record
The three BRLMs associated with this issue has handled 102 IPOs in the last three fiscals and out of which 27 IPOs closed below the issue price on listing date.
Conclusion
This HMC group arm is engaged in the providing the solutions to global e-mobility industry. Its domestic revenue is around 59% and export revenue is around 41% on an average for the reported periods. HML is operating in a highly competitive and fragmented segment. It posted average growth in its top and bottom lines for the reported periods. Based on its recent average financial data, the issue appears exorbitantly priced. It may carry the legacy of the HMC group in rewarding stakeholders in long run. Only well-informed/cash surplus investors may park moderate funds for medium to long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.