Raksan Transformers IPO Review (BSE SME) – Well-Informed Investors May Park Moderate Funds for Medium to Long Term
Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO of 5512800 equity shares of Rs. 10 each to mobilize Rs. 150.50 cr. at the upper cap. The IPO consists of 4412800 fresh equity shares (worth Rs. 120.47 cr. at the upper cap) and an Offer for Sale (OFS) of 1100000 equity shares (worth Rs. 30.03 cr. at the upper cap). The company has announced a price band of Rs. 258 – Rs. 273 per share. The minimum application to be made is for 800 shares and in multiples of 400 shares thereon, thereafter. The issue opens for subscription on September 10, 2026 and will close on September 15, 2026. The shares will be listed on BSE SME. The IPO constitute 26.39% of the post-IPO paid-up capital of the company. From the net proceeds of the fresh issue, the company will utilize Rs. 62.14 cr. for capex towards setting up of manufacturing unit, Rs. 7.28 cr. for repayment of certain borrowings, Rs. 35.00 cr. for working capital, and the rest for general corporate purposes.
The IPO is solely lead managed by Hem Securities Ltd., while Bigshare Services Pvt. Ltd. is the registrar to the issue. HEM group’s Hem Finlease Pvt. Ltd. is a market maker, and also a syndicate member.
After issuing initial equity capital at par value, the company issued further equity shares in the price range of Rs. 100 – Rs. 150 per share between July 2009, and January 2017. It has also issued bonus shares in the ratio of 18 for 1 in September 2025. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 0.00, Rs. 0.31, and Rs. 0.58 per share.
Post-IPO, company’s current paid-up equity capital of Rs. 16.48 cr. (16480600 equity shares) will stand enhanced to Rs. 20.89 cr. (20893400 equity shares). Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 570.39 cr.
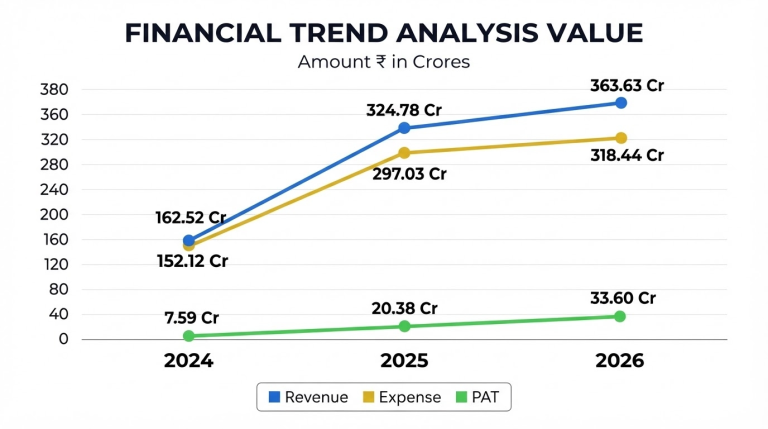
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted total income/ net profit, of Rs. 162.52 cr. / Rs. 7.59 cr. (FY24), Rs. 324.78 cr. / Rs. 20.38 cr. (FY25), Rs. 363.63 cr. / Rs. 33.60 cr. (FY26). The company posted growth in its top and bottom lines for FY25and FY26, that not only raise eyebrows, but also raises concern over its sustainability going forward. Rising trade receivables year-on-year, raise alarms. Its contingent liability stood at Rs. 64.24 cr. as of March 31, 2026.
For the last three fiscals, the company has reported an average EPS of Rs. 15.08 and an average RoNW of 42.45%. The issue is priced at a P/BV of 5.81 based on its NAV of Rs. 46.97 per share as of March 31, 2026, but its post-IPO NAV data is missing from the offer documents.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 16.98, and based on FY25 earnings, the P/E stands at 28.00. The issue appears fully priced based on its recent average earnings. This comparison appears to be an eyewash.
The company has posted PAT Margins of 4.72% (FY24), 6.28% (FY25), 9.25% (FY26) and RoCE margins of 34.00%, 43.09%, 46.72%, respectively for referred periods.
All amounts in Indian Rupees crores
The company has paid a dividend of 30% for FY25 and skipped for FY24 and FY26. It has already adopted a dividend policy in August 2025, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Marsons Ltd., Shilchar Techno, and Supreme Power, as its listed peers. They are currently trading at a P/E of 52.5, 34.1, and 27.1 (as of September 09, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Raksan Transformers Ltd. (RTL) is an ISO 9001:2015 certified company engaged in the manufacturing of transformers across different voltage ratings. Its product offerings include distribution transformers, power transformers, transformers for solar applications, and special purpose transformers. These transformers are utilized across multiple sectors to facilitate the transmission and distribution of electrical energy. It focuses on delivering quality and reliability in product range, supported by standardized manufacturing practices and compliance with applicable industry norms.
Transformers serve critical functions in power generation, transmission, and distribution networks, and are deployed in diverse industrial and infrastructure projects. The Company was incorporated in 1995, in the initial years of operation, it was primarily engaged in the repair and servicing of distribution and power transformers. Recognizing the growth potential in the power infrastructure sector and leveraging its experience, RTL established the manufacturing facility of transformers in the year 2005-06 from first manufacturing facility located at Plot no. 1413, HSIDC, Industrial Estate, Rai, District Sonepat. Subsequently, to meet increasing market demand and expand production capacity, it established a second manufacturing facility located at Plot No. 1676–1677, Sector-38, Phase-I, HSIIDC Industrial Estate, Rai, District Sonepat, Haryana.
In line with its strategic growth plans and to improve operational efficiency, The company has implemented a synergistic system of backward integration. As part of this integration, the group company, SHR Powers Private Limited, manufactures transformer tanks/bodies, which are key components utilized in the production of transformers. This integration enables it to optimize production processes, achieve cost efficiencies, enhance control over its supply chain, and reduce reliance on external suppliers. RTL follows standard practices in quality assurance, regulatory compliance, and process improvement to meet customer and industry requirements. Its approach has supported the development of long-term relationships with a wide range of customers, including government entities, utility companies, EPC contractors, and industrial clients. The Company is an approved vendor for over 20 entities, which includes power distribution corporations, public sector undertakings, and public utility companies. The company is following B2B, B2G and B2C model, but the first two has lion share in its revenues. As of June 30, 2026, it had 83 orders valued at Rs. 329.68 cr. As of the said date, it had 143 employees on its payroll.
Merchant Banker's Track Record
This is the 51st mandate from Hem Securities, in the last three fiscals (including the ongoing one). Out of the last 10 listings, 1 opened at par and the rest listed with a premium ranging from 1.80% to 90% on the listing date.
Conclusion
RTL is engaged in the manufacturing of transformers across different voltage ratings. It posted growth in its top and bottom lines for the reported periods. Boosted top and bottom lines raise eyebrows and concern over its sustainability. Based on its recent average financial data, the issue appears fully priced. Its order book stood at Rs. 329.68 cr. as of June 30, 2026. Well-informed investors may park moderate funds for medium to long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.