Maharaja & Speedex India IPO Review (BSE SME) – Only Well-Informed/Cash Surplus Investors May Park Moderate Funds for Medium Term
Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO of 4308000 equity shares of Rs. 10 each to mobilize Rs. 80.13 cr. at the upper cap. The IPO consists of 3446400 fresh equity shares worth Rs. 64.10 cr. (at the upper cap), and an Offer for Sale (OFS) of 861600 equity shares (worth Rs. 16.03 cr. at the upper cap). The company has announced a price band of Rs. 177 – Rs. 186 per share. The minimum application to be made is for 1200 shares and in multiples of 600 shares thereon, thereafter. The issue opens for subscription on September 10, 2026 and will close on September 15, 2026. The shares will be listed on BSE SME. The IPO constitute 26.36% of the post-IPO paid-up capital of the company. From the net proceeds of the fresh issue, the company will utilize Rs. 24.10 cr. for repayment/prepayment of certain borrowings, Rs. 21.42 cr. for capex on purchase of plant and machineries for existing facilities, and the rest for general corporate purposes.
The IPO is solely lead managed by Choice Capital Advisors Pvt. Ltd., while Maashitla Securities Pvt. Ltd. is the registrar to the issue. CHOICE group’s Choice Equity Broking Pvt. Ltd. is a market maker, and also a syndicate member.
After issuing initial equity capital at par value, the company issued further equity shares in the price range of Rs. 65309 – Rs. 70000 per share between January 2024, and March 2025. It has also issued bonus shares in the ratio of 1200 for 1 in January 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 0.01, and Rs. 59.26 per share.
Post-IPO, company’s current paid-up equity capital of Rs. 12.90 cr. (12898740 equity shares) will stand enhanced to Rs. 16.35 cr. (16345140 equity shares). Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 304.02 cr.
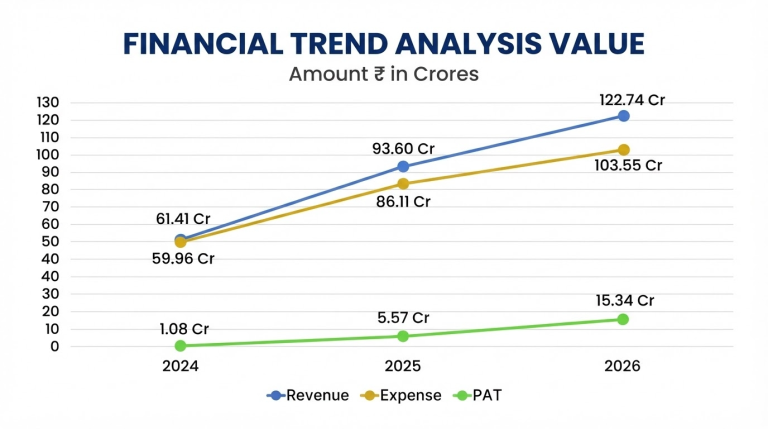
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted total income/ net profit, of Rs. 61.41 cr. / Rs. 1.08 cr. (FY24), Rs. 93.60 cr. / Rs. 5.57 cr. (FY25), Rs. 122.74 cr. / Rs. 15.34 cr. (FY26). The company posted surprised growth in its bottom lines from FY25 onwards, that not only surprises, but also raises concern over its sustainability going forward. Boosted bottom line for FY26 appears to be a window dressing to fetch fancy valuations for IPO. Rising trade receivables year-on-year, raise alarms.
For the last three fiscals, the company has reported an average EPS of Rs. 7.59 and an average RoNW of 68.17%. The issue is priced at a P/BV of 8.97 based on its NAV of Rs. 20.73 per share as of March 31, 2026, but its post-IPO NAV data is missing from the offer documents.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 19.81, and based on FY25 earnings, the P/E stands at 54.71. The issue appears greedily priced based on its recent average earnings.
The company has posted PAT Margins of 1.76% (FY24), 5.95% (FY25), 12.51% (FY26) and RoCE margins of 18.88%, 42.22%, 54.60%, respectively for referred periods. Outperforming margins against listed peers is a big surprise.
All amounts in Indian Rupees crores
The company has not paid any dividends for the reported periods of the offer document. It will adopt a prudent dividend policy, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Borosil Ltd., Cello World, as its listed peers. They are currently trading at a P/E of 43.4, and 24.2 (as of September 10, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Maharaja & Speedex India Ltd. (MSIL) is a drinkware manufacturing and distribution company focused on stainless-steel bottles and allied drinkware products, catering to both retail consumers and institutional customers across India. The Company is engaged in the manufacturing, branding, marketing and distribution of stainless-steel bottles and value-added drinkware products, with a diversified portfolio designed to address evolving consumer preferences for durable, hygienic and reusable drinkware solutions. The Company’s product portfolio is broadly classified into Standard Products and Novelty Products. Standard Products include stainless steel bottles catering to routine usage, while Novelty Products comprise tumblers, feeding bottles and gym shakers, designed to meet evolving consumer preferences.
These products are offered across multiple price points and consumer segments including mass, premium and lifestyle categories, enabling the Company to cater to a broad customer base. Over the past few years, the Company has expanded its product mix to include value-added and specialized drinkware products, reflecting growing consumer awareness around health, sustainability and the shift from plastic-based products to stainless-steel alternatives. In addition to its branded product offerings, the Company undertakes original equipment manufacturing (OEM) and private-label manufacturing, providing customized drinkware solutions for corporate gifting programs, institutional buyers and brand partners. These capabilities enable the Company to serve both business-to-consumer (“B2C”) and business-to-business (“B2B”) markets, while building long-term relationships with distributors, retailers and institutional clients.
The Company operates an integrated, asset-backed business model supported by in-house manufacturing capabilities, with its manufacturing operations primarily undertaken through its subsidiary. This structure enables the Company to maintain effective control over product quality, production processes and product development. The manufacturing facilities operated by its subsidiary are equipped with modern machinery and advanced production lines designed to support efficient large-scale manufacturing, while also allowing for product customization across a diverse range of drinkware categories.
The Company continues to focus on improving manufacturing efficiencies, expanding its product offerings and introducing new designs and variants in line with changing consumer preferences. The Company’s operations are supported by a Pan-India distribution network, which enables it to reach customers across multiple geographies. The distribution network comprises 101 distributors across 17 states and 2 Union Territories. including Maharashtra, Uttar Pradesh, Rajasthan and Punjab, supported by presence in modern trade formats and a growing footprint across online sales channels. This integrated distribution approach allows the Company to strengthen its market reach while ensuring availability of its products across diverse sales channels.
Through its integrated manufacturing capabilities, diversified product portfolio and expanding distribution network, the Company seeks to strengthen its presence in the stainless-steel drinkware market. The Company continues to focus on product innovation, expansion of value-added categories, strengthening distribution reach and operational efficiencies, which it believes will support its long-term growth and scalability. As of March 31, 2026, it had 431 employees on its payroll.
Merchant Banker's Track Record
This is the 11th mandate from Choice Capital Advisors, in the last three fiscals (including the ongoing one). Out of the last 10 listings, 1 opened at discount, and the rest listed with a premium ranging from 0.045% to 90.00% on the listing date.
Conclusion
MSIL is engaged in manufacturing and distribution of stainless-steel drinkware and other allied products. The company is operating in a highly competitive and fragmented segment. The company marked steady growth in its top and bottom lines for the reported periods. Boosted margins of FY26 appears window dressing to fetch fancy valuation for the IPO. Based on its recent average financial data, the issue appears greedily priced. Only well-informed/cash surplus investors may park moderate funds for medium term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.