Fly-Hi Maritime IPO Review (BSE SME) – Only Well-Informed/Cash Surplus/Risk Seekers May Park Moderate Funds for Medium Term
Preface
This company is coming out with its maiden IPO for Rs. 52.63 cr. and the issue is opening on September 01, 2026. Surprisingly, its IPO ad appears in the daily newspaper only on Monday, i.e., August 31, 2026, and offer documents were not available on the designated exchange website till this morning. The offer document is dated August 26, 2026, but its uploading was delayed on social media/designated exchange, which appears to be a deliberate move. Is such lacuna on compliance is tolerable?
Issue Details / Capital History
The company is coming out with its maiden combo IPO of 5160000 equity shares of Rs. 5 each at a fixed price of Rs. 102 per share to mobilize Rs. 52.63 cr. The issue comprises fresh equity issue of 4160400 shares worth Rs. 42.44cr. and an Offer for Sale (OFS) of 999600 equity shares worth Rs. 10.19 cr. The minimum application to be made is for 2400 shares and in multiples of 1200 shares thereon, thereafter. The issue opens for subscription on September 01, 2026 and will close on September 03, 2026. The shares will be listed on BSE SME. The IPO constitute 36.39% of the post-IPO paid-up capital of the company. The company is spending Rs. 6.03 cr. for this IPO process (fresh equity issue), and from the net proceeds of the fresh issue, the company will utilize Rs. 24.24 cr. for working capital, Rs. 4.00 cr. for repayment/prepayment of certain borrowings, Rs. 1.80 cr. for talent acquisition for business marketing and development, and Rs. 6.36 cr. for general corporate purposes.
The IPO is solely lead managed by Corporate Makers Capital Ltd., while KFin Technologies Ltd. is the registrar to the issue. Bhaijee Broking & Investments Pvt. Ltd. is the market maker. The issue is underwritten to the tune of 15% by Corporate Makers Capital and up to 85% by Erudore Capital Pvt. Ltd.
After issuing initial equity capital at par value (on the basis of Rs. 5 FV), the company also issued bonus shares in the ratio of 500 for 1 in November 2025. The average cost of acquisition of shares by the promoters is Rs. NIL, and Rs. 0.02 per share.
Post-IPO, company’s current paid-up equity capital of Rs. 5.01 cr. (10020000 equity shares) will stand enhanced to Rs. 7.09 cr. (14180400 equity shares). Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 144.64 cr.
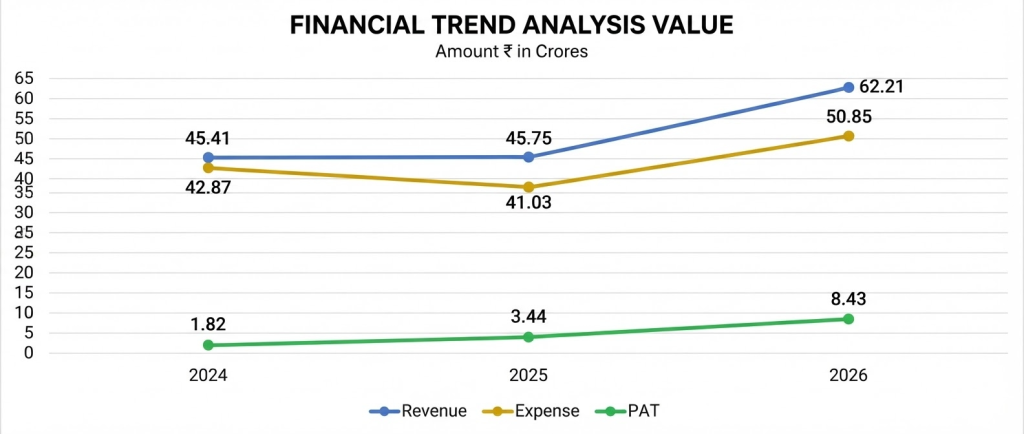
On the financial performance front, for the last three fiscals, the company has posted total income/ net profit, of Rs. 45.41 cr. / Rs. 1.82 cr. (FY24), Rs. 45.75 cr. / Rs. 3.44 cr. (FY25), Rs. 62.21 cr. / Rs. 8.43 cr. (FY26). The company posted surprised growth in its bottom lines from FY25 onwards. Surge in bottom line for FY25 on a static top line raised eyebrows, and boosted bottom line for FY26 appears to be a window dressing to fetch fancy valuations for IPO. Rising trade receivables year-on-year, raise alarms.
For the last three fiscals, the company has reported an average EPS of Rs. 5.66 and an average RoNW of 51.07%. The issue is priced at a P/BV of 5.69 based on its NAV of Rs. 17.92 per share as of March 31, 2026, and at a P/BV of 2.39 based on its post-IPO NAV of Rs. 42.59 per share.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 17.17, and based on FY25 earnings, the P/E stands at 41.96. The issue appears greedily priced based on its recent average earnings.
The company has posted PAT Margins of 4.04% (FY24), 7.59% (FY25), 13.58% (FY26) and RoCE margins of 37.61%, 45.18%, 67.22%, respectively for referred periods.
All amounts in Indian Rupees crores
The company has not paid any dividends for the reported periods of the offer document. It will adopt a prudent dividend policy, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has no listed peers to compare with.

Fly-Hi Maritime Travels Ltd. (FMTL) is managing end to end travel arrangements for crew of commercial shipping companies, ensuring that the crew members move seamlessly from their home country to the port of boarding. It manages their airline tickets, ground travel, hotel stay, visa application etc until they reach the desired port of boarding. Every movement of the crew members directly impacts the vessel schedules, compliances and operations. FMTL’s role is to absorb this complexity on behalf of shipping companies by planning and making end to end travel arrangements for the crew members and by offering them 24/7 support during their travel from their home country to the port of boarding.
Modern shipping fleets operate with crew of mixed nationalities and therefore each crew member has to have a tailor made travel itinerary to ensure their arrival to the port of boarding as per the desired time and schedule. It works with commercial shipping companies to move their crew from countries to the port of boarding, it has commercial shipping companies as its customers from more than 6 countries.
The company has a centralized operational model driven by a lean and efficient team. It has centralized its operations in Mumbai office which is its corporate office. The company arranges supply of hotels, airlines, car rentals, transfer providers, cruise companies and other via direct connectivity or through third party aggregators. It has appointed a distributor in UAE to manage a few customers based in foreign countries due to their international requirements. FMTL’s customers include a few marquee names in the commercial shipping industry. It is an International Air Transport Association (IATA) accredited company. As of July 31, 2026, it had 54 employees on its payroll.
Merchant Banker's Track Record
This is the 14th mandate from Corporate Makers Capital Ltd., in the last three fiscals (including the ongoing one). Out of the last 13 listings, 7 opened at discount, 4 at par, and the rest listed with a premium ranging from 4.35% to 53.38% on the listing date. The merchant banker has a poor track record.
Conclusion
FMTL is engaged in managing end-to-end travel arrangements for crew of commercial shipping companies. It marked improved bottom lines on a static top line for FY24 and FY25. Boosted bottom line for FY26 raise eyebrows and appears to be a window dressing to pave fancy valuations for the IPO. Based on its recent average financial data, the issue appears greedily priced. Small paid-up equity capital post-IPO indicates longer gestation period for migration. Only well-informed/cash surplus/risk seekers may park moderate funds for medium term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.