Apana Logistics IPO Review (BSE SME)
Issue Details / Capital History
The company is coming out with its maiden IPO of 5690000 equity shares of Rs. 10 each at a fixed price of Rs. 60 per share to mobilize Rs. 34.14 cr. The minimum application to be made is for 4000 shares and in multiples of 2000 shares thereon, thereafter. The issue opens for subscription on September 07, 2026 and will close on September 09, 2026. The shares will be listed on BSE SME. The IPO constitute 32.50% of the post-IPO paid-up capital of the company. The company is spending Rs. 4.10 cr. for this IPO process, and from the net proceeds of the fresh issue, the company will utilize Rs. 25.00 cr. for capex on purchase of reach stackers, Rs. 5.04 cr. for general corporate purposes.
The IPO is solely lead managed by Corporate Makers Capital Ltd., while KFin Technologies Ltd. is the registrar to the issue. Prabhat financial Services Ltd. is the market maker. The issue is underwritten to the tune of 15.01% by Corporate Makers Capital and up to 84.99% by Prabhat Financial Services Ltd.
After issuing entire initial equity capital at par value, the company also issued bonus shares in the ratio of 9 for 1 in March 2020, and 5 for 1 in February 2025. The average cost of acquisition of shares by the promoters is Rs. NIL per share.
Post-IPO, company’s current paid-up equity capital of Rs. 11.82 cr. (11820000 equity shares) will stand enhanced to Rs. 17.51 cr. (17510000 equity shares). Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 105.06 cr.
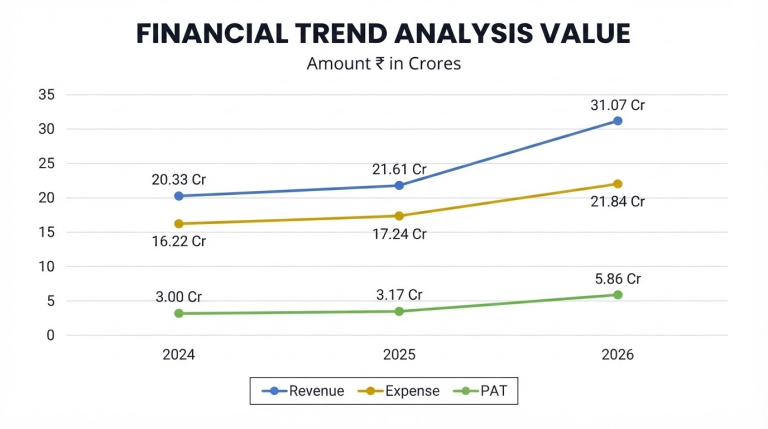
On the financial performance front, for the last three fiscals, the company has posted total income/ net profit, of Rs. 20.33 cr. / Rs. 3.00 cr. (FY24), Rs. 21.61 cr. / Rs. 3.11 cr. (FY25), Rs. 31.07 cr. / Rs. 5.87 cr. (FY26). The company posted surprised growth in its bottom lines for FY26, that not only surprises, but also raises concern over its sustainability going forward. Boosted bottom line for FY26 appears to be a window dressing to fetch fancy valuations for IPO. Rising trade receivables year-on-year, raise alarms. Its contingent liability stood at Rs. 0.71 cr. as of March 31, 2026.
For the last three fiscals, the company has reported an average EPS of Rs. 3.78 and an average RoNW of 29.62%. The issue is priced at a P/BV of 3.50 based on its NAV of Rs. 17.15 per share as of March 31, 2026, and at a P/BV of 1.93 based on its post-IPO NAV of Rs. 31.08 per share.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 17.14, and based on FY25 earnings, the P/E stands at 33.90. The issue appears greedily priced based on its recent average earnings.
The company has posted PAT Margins of 14.94% (FY24), 14.49% (FY25), 19.01% (FY26) and RoCE margins of 29.00%, 26.57%, 45.00%, respectively for referred periods.
All amounts in Indian Rupees crores
The company has not paid any dividends for the reported periods of the offer document. It will adopt a prudent dividend policy, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Premier Roadlines, VRL Logistics, as its listed peers. They are currently trading at a P/E of 6.35, and 19.5 (as of September 04, 2026). However, they are not truly comparable on an apple-to-apple basis.
Apana Logistics Ltd. (ALL) is engaged in the business of providing logistics support for handling and transportation of containers, wherein the fleet is inclusive of reach stackers, forklifts, truck-trailers (TT). Its service offering is diversified which include, Container handling at CFS/ICD/port, road transportation, cargo handling at third-party warehouses, and repair, operation & maintenance of trucks-trailers (TT).
The Company also holds experience in operations and maintenance services to ensure efficient handling of reach stackers. ALL’s key services include container handling, operation and management of truck-trailers. The company serves some of the top leading CFS/ICD/Port Operators in India. Its long-standing relationships with CFS, ICD’s and Ports and its experience in container handling through reach stackers, cargo handling and understanding of customers’ supply chain, regional market dynamics for transportation, enable it to deliver cost and time effective solutions for customers.
Its experienced management team has required skills, which enabling it to provide these services to customers efficiently. As on March 31, 2026, it has maintained and owned fleet size of Thirty-Three (33) truck-trailers, five (5) reach stackers and two (2) cranes. The company maintains an aggressive bidding strategy, active participation in tenders and leveraging its expertise to accommodate such projects simultaneously.
As of March 31, 2026, its order book stood at Rs. 80.35 cr., to be executed between March 2027 to March 31, 2030. As of June 30, 2026, it had 62 employees on its payroll.
Merchant Banker's Track Record
This is the 15th mandate from Corporate Makers Capital Ltd., in the last three fiscals (including the ongoing one). Out of the last 13 listings, 7 opened at discount, 4 at par, and the rest listed with a premium ranging from 4.35% to 53.38% on the listing date. The merchant banker has a poor track record.
Conclusion
ALL is engaged in the business of providing logistics support for handling and transporting containers. Its order book stood at Rs. 80.35 cr. as of March 31, 2026. The company is operating in a highly competitive and fragmented segment. After static top and bottom lines for FY24 and FY25, it posted big surge in its performance, that raise eyebrows and concern over its sustainability. Based on its recent average financial data, the issue appears greedily priced. Merchant Banker has a poor track record so far. There is no harm in skipping this pricey offer.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.