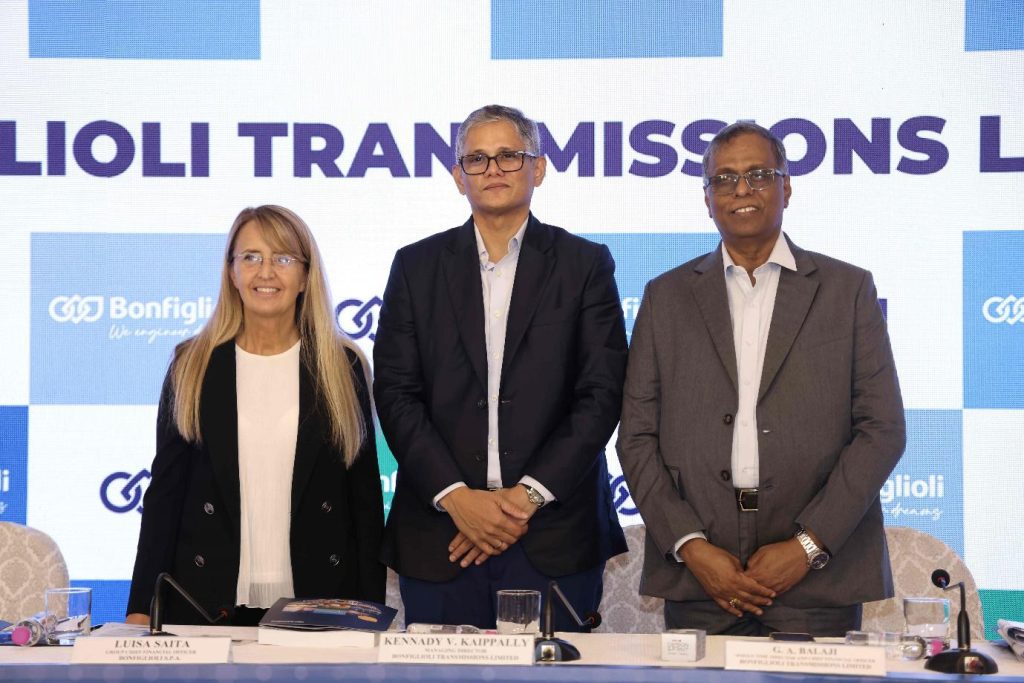
Bonfiglioli Transmissions IPO Review by Dilip Davda
Issue Details / Capital History
The company is coming out with its maiden book building route secondary IPO of 43239042 equity shares worth Rs. 2533.81 cr. at the upper cap. The company has announced a price band of Rs. 558 – Rs. 586 per equity shares of Rs. 10 each. The issue opens for subscription on October 15, 2026, and will close on October 19, 2026. The minimum application to be made is for 25 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 23% of the post-IPO paid-up equity capital. This being a pure Offer for Sale (OFS), no funds are going to company. The issue is being made to provide exit to some of its stakeholders, and unlock the listing benefits.
The company has reserved 50000 equity shares (worth Rs. 2.93 cr. at the upper cap) for its eligible employees, and offering them a discount of Rs. 29 per share. From the rest, it has allocated not more than 50% for QIBs, not less than 15% for HNIs, and not less than 35% for Retail investors.
The joint Book Running Lead Managers (BRLMs) to this issue are Axis Capital Ltd., BNP Paribas, ICICI Securities Ltd., Jefferies India Pvt. Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue.
Having issued initial equity shares at par value, the company has issued further shares in the price range of Rs. 53.60 – Rs. 68 per share (based on FV of Rs. 10), between December 2017 and December 2021. It has also issued bonus shares in the ratio of 1 for 2 in January 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 6.77 per share.
Post-IPO, its current paid-up equity capital of Rs. 188.00 cr. (187995834 equity shares) will stand same as this is a hundred percent secondary issue. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 11016.56 cr.
On the financial performance front, for the last calendar years, the company has posted a total income/net profit, of Rs. 1701.80 cr. / Rs. 146.67 cr. (CY23), Rs. 1861.16 cr. / Rs. 191.60 cr. (CY24), and Rs. 2023.59 cr. / Rs. 237.87 cr. (CY25). For H1 of CY26 ended on June 30, 2026, it earned a net profit of Rs. 148.58 cr. on a total income of Rs. 1139.17 cr. The company posted growth in its performances for the reported periods. Higher Trade Receivables raise concern. Its contingent liabilities stood at Rs. 3.08 cr. as of June 30, 2026.
For the last three CYs, the company has posted an average EPS of Rs. 7.90 and an average RoNW of 22.45%. The issue is priced at a P/BV of 10.65 based on its NAV of Rs. 55.02 as of June 30, 2026, as well as on the basis of post-IPO NAV per share at the upper cap.
If we attribute CY26 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 37.07. Based on CY26 earnings, the P/E stands at 46.32 The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 8.62% (CY23), 10.29% (CY24), 11.76% (CY25), 13.04% (H1-CY26), and RoCE margins of 24.53%, 30.05%, 34.05%, 20.03%, respectively, for the referred periods.
The company has paid a dividend of 50% (CY23), 55% (CY24), 74% (CY25). It has adopted a dividend policy in February 26, based on its earnings and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Elecon Engg., Shanthi Gears, Schaeffler India, Timken India, as its listed peers. They are currently trading at a P/E of 30.3, 62.3, 44.5, and 53.9 (as of October 12, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.

Bonfiglioli Transmissions Ltd. (BTL) is one of India’s largest technology-led mechanical and electro-mechanical power transmissions and industrial drive solutions providers by revenue for the six months period ended June 30, 2026 (Source: F&S Report). The company manufactures a wide range of mission-critical and highly precision engineered gear motors, gearboxes and drive systems used across diverse end-user markets (Source: F&S Report). Its legacy and reputation lie in the Bonfiglioli brand, which has a worldwide presence of nearly 70 years, and which it has established in India through more than 25 years of operations. Its Corporate Promoter, Bonfiglioli S.p.A. is headquartered in Italy, and according to the F&S Report, is one of the largest technologically advanced players globally in the mechanical and electro-mechanical power transmissions and industrial drive solutions industry with consolidated revenues of Euro 1172.94 million (Rs. 115.56 billion) for the year ended December 31, 2025. It focuses on the development, manufacture and distribution of gearboxes and drive systems to cater to the needs of industrial processes, automation, off-highway mobility solutions and renewable energy applications.
As at the date of this Red Herring Prospectus, the Bonfiglioli Group has operations spanning across 80 countries through 18 production sites, seven R&D centres, a network of more than 550 distributors and resellers, and a workforce of more than 5000 employees, with 21 patents granted under the name of Bonfiglioli S.p.A. The markets BTL caters to are broadly categorized into three business verticals: Industry and Automation Solutions, Off-Highway Mobility and Wind Industries, based on the end-use applications. According to the F&S Report, it is the largest manufacturer in India of gearboxes (gear motors below 15 kNm) and drives catering to OEMs and end-users in the Industry & Automation, Off-Highway Mobility and Wind Industries in India as of June 30, 2026, in terms of revenue from operations. It is also among the leading manufacturers of planetary gearboxes in India in the year ended December 31, 2025 by revenue. (Source: F&S Report).
The company enjoys market share of 25% in Industry and Automation solutions, 32% for off-highway mobility industry, and 67.9% in Wind Industry. Its customer base comprises OEMs that it directly supplies products to under its Industry & Automation vertical, and OEMs that its co-engineers with under its Off-Highway Mobility Industry and Wind Industry verticals. The company caters to a wide range of industries under its Industry & Automation vertical with no single industry contributing more than 10% of its revenue under the Industry & Automation vertical in the six months periods ended June 30, 2026 and in Fiscals 2025, 2024, and 2023. The Industry & Automation vertical benefits from its strong and loyal dealer network which, as of June 30, 2026 comprised of 44 dealers of which 16 dealers had been engaged with it for 20 years or more.
Furthermore, of the 44 dealers it engaged with, 36 dealers engaged with it on an exclusive basis as of June 30, 2026. It is an integral part of its customer’s product development cycles under the Off-Highway Mobility and Wind Industries, working closely with them from design stage to create customized, technology intensive products to meet their bespoke end-use specifications. In the six months period ended June 30, 2026, it served more than 930 customers directly and had been engaged by seven out of its top 10 OEM customers (in terms of revenue from operations in Fiscal 2025) for more than 10 years, demonstrating the lasting value and reliability of its service commitments. The company also had a diverse range of customers with its top 10 OEM customers representing less than 31.72% of its revenue from operations in the six months periods ended June 30, 2026 and in each of Fiscals 2025, 2024, and 2023. The company also engages with dealers for onward sales to OEMs under its Industry & Automation vertical. The company approaches customers directly through pan-India sales network that comprised 13 sales offices and 64 sales employees as of June 30, 2026.
Furthermore, of the 44 dealers it engaged with, 36 dealers engaged with it on an exclusive basis as of June 30, 2026. It is an integral part of its customer’s product development cycles under the Off-Highway Mobility and Wind Industries, working closely with them from design stage to create customized, technology intensive products to meet their bespoke end-use specifications. In the six months period ended June 30, 2026, it served more than 930 customers directly and had been engaged by seven out of its top 10 OEM customers (in terms of revenue from operations in Fiscal 2025) for more than 10 years, demonstrating the lasting value and reliability of its service commitments. The company also had a diverse range of customers with its top 10 OEM customers representing less than 31.72% of its revenue from operations in the six months periods ended June 30, 2026 and in each of Fiscals 2025, 2024, and 2023. The company also engages with dealers for onward sales to OEMs under its Industry & Automation vertical. The company approaches customers directly through pan-India sales network that comprised 13 sales offices and 64 sales employees as of June 30, 2026.
BTL benefits significantly by being a part of the Bonfiglioli Group, which enables it to leverage its global customer relationships and supply products and solutions to the Indian businesses of international players. With access to the extensive research and development expertise of Bonfiglioli S.p.A. (“BSPA”), including a broad portfolio of innovative products, it is able to meet the localized requirements of customers. As of June 30, 2026, the Bonfiglioli Group had seven R&D centers globally including in India, Italy, Germany and China, that employed 376 employees. The company regularly liaises with the R&D and IT center located in Chennai, Tamil Nadu, India (“India R&D Centre”) which is housed under Bonfiglioli Technology Space Private Limited (“BTSPL”), a company forming part of the Bonfiglioli Group. The India R&D Centre has test facilities for products across all three of its business verticals, and as of June 30, 2026, it was the only test laboratory in India equipped to test yaw and pitch drives for wind turbines (Source: F&S Report).
The proximity of its manufacturing operations with Bonfiglioli Group’s global R&D ecosystem enables faster product development through strong design manufacturing alignment and early supplier involvement, resulting in faster time-to-market and enhancing its responsiveness to India-specific customer requirements, establishing its position as a specialized solutions provider in India. The India R&D Centre is the only R&D centre in the Bonfiglioli Group that caters to all three end-user verticals, which allows it to leverage its development capabilities across entire portfolio of products and services.
As of June 30, 2026, BTL operated three facilities in India, two of which were in Tamil Nadu (at Thirumudivakkam and Mannur) and one was in Maharashtra (in Talegaon), that manufactured a combined total of 341133 units of gear motors and gearboxes in Fiscal 2025. Over the years, it has consistently increased sourcing parts and materials from domestic suppliers to strengthen its localization strategy. As of June 30, 2026, it had 215 suppliers in India and 70 suppliers outside India. In the six months periods ended June 30, 2026 and in Fiscals 2025, 2024 and 2023, purchases of raw materials and components from the domestic market represented 68.32%, 70.00%, 68.71% and 64.12%, of its total purchase of raw material and components, respectively, demonstrating its commitment to sourcing from India. It sources from a diverse network of suppliers, with no single supplier providing more than 20.00% of its purchases in the six months periods ended June 30, 2026 and Fiscals 2025, 2024 and 2023.
BTL follows a multi-dimensional approach to quality assurance that involves ensuring quality compliance at each level of its operations. The company also provides after-sales services to customers through two dedicated channels: (a) team of in-house service engineers stationed at its 13 sales offices across India (three of which are located at its manufacturing locations in Thirumudivakkam (Tamil Nadu), Mannur (Tamil Nadu), and Talegaon (Maharashtra) that aggregated to 15 engineers as of June 30, 2026; and (b) a broad base of 13 third-party authorized service facilities that had an aggregate of 24 service engineers as of June 30, 2026. It strives to, on average, respond to complaints within the next working day, significantly increasing product uptime and lifecycle value.
Its 25 years of operating experience in India, global R&D, manufacturing capabilities, and customerrelationships, has enabled it to deliver growth over the years in terms of its profitability, return on equity and return on capital employed. As of June 30, 2026, it had 1032 employees (including contract workers).
Merchant Banker's Track Record
The four BRLMs associated with this issue have handled 104 public issues in the past three years, out of which 29 issues closed below the offer price on listing date.
Conclusion
BTL is one of India’s largest technology-led mechanical and electromechanical power transmission and industrial drive solutions provider. The company has global operations spanning across 80 countries with 18 production sites,7 R & D centres, network of 550+ distributors. The company posted growth in its top and bottom lines for the reported periods. It enjoys virtual monopoly for variety of gear box manufacturing with 67.9% market share in wind industry. Based on its recent average financial data, the issue appears fully priced. Well-informed investors can park funds for medium to long term, in this dividend paying company.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.