Lohia Corp IPO Review
Lohia Corp Ltd. (LCL) is among the leading global manufacturers of machinery and equipment for technical textiles in terms of revenue in 2024, with a strong focus on solutions for producing polypropylene (“PP”) and high-density polyethylene (“HDPE”) woven fabric and sacks (“Raffia”). (Source: F&S Report) In 2024, it ranked among the top global players by revenue, with a 15.4% share of the global woven Raffia machinery market by value. (Source: F&S Report) LCL is a market leader in the domestic woven Raffia machines market, with a dominant market share of 40.7% by value in Fiscal 2025. (Source: F&S Report)
As of March 31, 2026, its manufacturing facilities had an installed capacity to produce 240 tapelines, 13,800 circular looms and 108,000 tape winders annually. It manufactures a comprehensive and diverse suite of machinery such as tape extrusion lines, circular loom, coating and lamination lines, printing machines, conversion machines, multifilament yarn machines, twister winders, monofilament extrusion lines and recycling machines, amongst others, as well as spare parts. The company provides end-to-end solutions for the entire ecosystem of woven fabric, offering services from ‘concept to commissioning’, throughout the complete production lifecycle required for the Raffia industry.
It manufactures winders and rewinders for high performance fibres and has also ventured into extrusion lines to produce technical monofilaments with diversified applications such as textiles, agriculture and sports. The machines LCL manufactures enable its customers to deliver solutions across a diverse spectrum of end -user industries, catering to varied applications. Woven fabric machines are used in a wide range of packaging applications across various industries, including the packaging of cement, fertilizer, chemicals, polymer, food grain and minerals, as well as in the production of shopping bags, leno bags, flexible intermediate bulk containers (“FIBC”) and container liners; they are also utilized in a variety of non-packaging applications, such as wrapping fabric, roof underlayment, lumber wrap, pond liner, tarpaulin, geotextile, geogrid, ground cover, carpet backing, ropes and twines. (Source: F&S Report).
The company owns and operates six machine manufacturing facilities, with four in India and one each in USA and Italy, along with one live experience centre in India. Of its Indian manufacturing facilities, two are located in Kanpur, Uttar Pradesh along with the live experience centre (where it manufactures FIBCs), and two are located in Bengaluru, Karnataka. Its manufacturing facility in USA is located in Burlington, North Carolina and manufacturing facility in Italy is located in Como, Italy.
It has developed in-house capabilities to deliver evolving technologies and continue to invest in research and development. As of the date of this Red Herring Prospectus, the Company, with its Subsidiaries and the Demerged Company have registered 54 trademarks. Further, the Company has been granted 71 patents in India and 56 patents outside India, and has eight design registrations in India. As on the date of this Red Herring Prospectus, the Company, with its Subsidiaries and the Demerged Company have applied for 24 trademark registrations and further, it has applied for 19 patents in India, which are currently pending. LCL supplies machinery and equipment through an exclusive global sales network, and in Fiscals 2026, 2025 and 2024, had supplied its products to around 100 countries. However, the company marked inconsistency in its domestic and export sales rations for the reported periods. As of March 31, 2026, it had 2010 employees on its payroll, and additional 1099 contractual employees. As of March 31, 2026, its order book stood at Rs. 1358.52 cr.

Issue Details / Capital History
The company is coming out with its maiden book building route secondary IPO of 25931407 equity shares (worth Rs. 1102.08 cr. at the upper cap). The company has announced a price band of Rs. 404 – Rs. 425 per equity shares of Re. 1 each. The issue opens for subscription on July 23, 2026, and will close on July 27, 2026. The minimum application to be made is for 35 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 24.54% of the post-IPO paid-up equity capital. This being a pure OFS issue, no funds are going to the company. The issue is being made to provide exit to some of its existing stakeholders and unlock listing benefits including visibility.
The company has reserved 200000 equity shares (worth Rs. xx cr. at the upper cap) and offering them a discount of Rs. 40 per share. From the rest, it has allocated not more than 75% for QIBs, not less than 15% for HNI investors and not less than 10% for Retail investors.
The joint Book Running Lead Managers (BRLMs) to this issue are Equirus Capital Ltd., Motilal Oswal Investment Advisors Ltd., and MUFG Intime India Pvt. Ltd. is the registrar to the issue.
The company has issued/converted initial equity shares at par value, and has also issued bonus shares in the ratio of 10 for 1 in February 1993, and 3 for 2 in August 2022. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 0.02, Rs. 0.04, Rs. 0.05, Rs. 0.07, and Rs. 0.91, per share.
Post-IPO, its current paid-up equity capital of Rs. 10.57 cr. will remain same as this is pure OFS. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 4490.13 cr.
IPO Lead Managers & Registrar
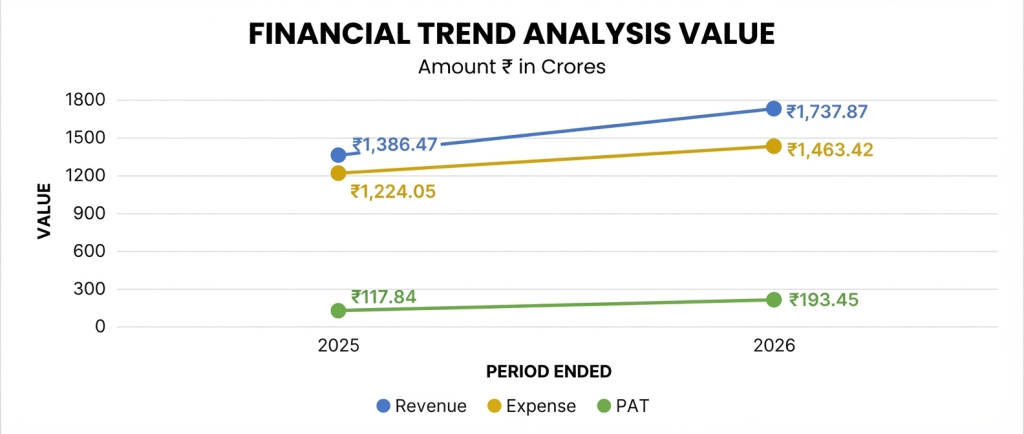
On the financial performance front, for the last two fiscals, the company has (on a consolidated basis) posted a total income/net profit/ - (loss), of Rs. 1386.47 cr. / Rs. 117.84 cr. (FY25), and Rs. 1737.87 cr. / Rs. 193.45 cr. (FY26). The company posted growth in its top and bottom lines for the reported consolidated periods. For FY24, on a standalone basis, it posted total income of Rs. NA and marked net loss of Rs. - (0.01) cr. But on a special purpose combined and carved-out statement, it marked total income of Rs. 1173.60 cr. with a net profit of Rs. 29.76 cr. Post consolidation, with improved synergies, it has performed well and heading for a bright prospect ahead. Its consolidated contingent liabilities of Rs. 48.74 cr. as of March 31, 2026 raise concern.
For the last three fiscals, the company has posted an average EPS of Rs. NA and an average RoNW of 73.83 %. The issue is priced at a P/BV of 8.61 based on its NAV of Rs. 49.37 as of March 31, 2026, as well as on post-IPO basis.
If we attribute FY26 earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 23.21. Based on FY25 earnings, the P/E stands at 38.12. The issue appears fully priced.
For the reported periods, the company has posted PAT margins of 2.54 % (FY24- Spl purpose combined carve-out statement), 8.50% (FY25-consolidated), 11.13% (FY26-consolidated), and RoCE margins of 10.45%, 30.45%, 40.92%, respectively for the referred periods.
All amounts in Indian Rupees crores
The company has paid a dividend of 175% (FY26), and 150% (for ongoing fiscal so far). It has already adopted a dividend policy, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Mamata Machinery, Jyoti CNC, Windsor Machines, as its listed peers. They are currently trading at a P/E of 56.0, 54.4, and 2506.0 (as of July 20, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Merchant Banker's Track Record
The two BRLMs associated with this issue have handled 40 IPOs in the last three fiscals out of which 11 issues closed below the issue price on the listing date.
Conclusion
LCL is one of the leading global manufacturers of machinery and equipments for technical textiles of different variants. The company marked improved performances post consolidation of its operations and synergies. It enjoys good market share for its difference products in domestic as well as global markets. As of March 31, 2026, it had an order book worth Rs. 1358.52 cr. Based on its recent financial data; the issue appears fully priced. Well-informed investors may park funds for medium to long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.