Symbiotec Pharmalab IPO Review - Well-Informed Investors can Park Funds for Medium to Long Term Rewards
Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO worth Rs. 1757.00 cr. (approx. 17783401 equity shares at the upper cap). The IPO consists of equity shares worth Rs. 150.00 cr. (approx. 1518219 equity shares at the upper cap) and an Offer for Sale (OFS) worth Rs. 1607.00 cr. (approx. 16265182 equity shares at the upper cap). The company has announced a price band of Rs. 938– Rs. 988 per equity shares of Rs. 2 each. The issue opens for subscription on August 24, 2026, and will close on August 27, 2026. The minimum application to be made is for 15 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 27.68% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 112.50 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes.
The joint Book Running Lead Managers (BRLMs) to this issue are JM Financial Ltd., Avendus Capital Pvt. Ltd., Motilal Oswal Investment Advisors Ltd., and Nomura Financial Advisory and Securities (India) Pvt. Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. JM Financial Services Ltd., Spark Institutional Equities Pvt. Ltd., and Motilal Oswal Financial Services Ltd. are syndicate members.
The company has reserved equity shares worth Rs. 3.00 cr. (approx. 30364 equity shares) for its eligible employees, and offering them a discount of Rs. 90 per share. From the rest, it has allocated not more than 50% for QIBs, not less than 35% for Retail Investors, and 15% for HIN investors.
After issuing/converting initial equity shares at par value, the company has issued further equity shares in the price range of Rs. 4.60 – Rs. 276 per share (on the basis of Rs. 2 FV) between September 2005, and March 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. NIL, Rs. 49.43, Rs. 72.37, Rs. 147.21, Rs. 273.04, and Rs. 276.00 per share.
Post-IPO, its current paid-up equity capital of Rs. 12.55 cr. (62734851 equity shares) will stand enhanced to Rs. 12.85 cr. (64253070 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 6348.20 cr.
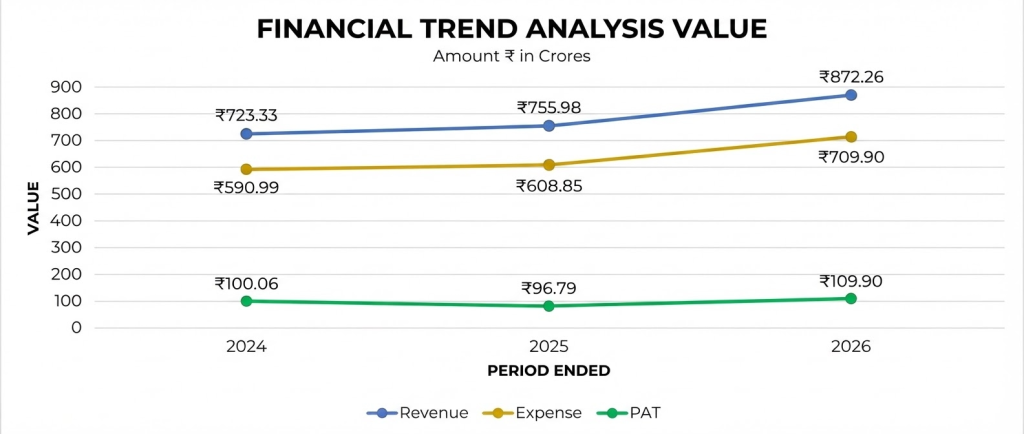
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 723.33 cr. / Rs. 100.06 cr. (FY24), Rs. 755.98 cr. / Rs. 96.79 cr. (FY25), and Rs. 872.26 cr. / Rs. 109.90 cr. (FY26). The company posted steady growth in its top and bottom lines for the reported periods, except for FY25, where it posted lower net on higher top line. According to the management, this is on account of provisioning of depreciation and amortization adjustments. With the major expansion is likely to be on stream soon, it is expecting to outperform the financial results posted for recent years.
For the last three fiscals, the company has posted an average EPS of Rs. 18.35 (basic) and an average RoNW of 10.99 %. The issue is priced at a P/BV of 5.35 based on its NAV of Rs. 184.69 as of March 31, 2026, and at a P/BV of 4.85 based on its post-IPO NAV of Rs. 203.66 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 57.78. Based on FY25 earnings, the P/E stands at 65.60. The issue appears aggressively priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 13.83% (FY24), 12.80% (FY25), 12.60% (FY26), and RoCE margins of 14.03%, 11.80%, 11.56%, respectively for the referred periods.
All amounts in Indian Rupees crores
Dividend Policy
The company has not paid any dividends for the reported periods of the offer document. It has already adopted a dividend policy in December 2025, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Concord Biotech, Divi’s Lab., Cohance Life, Laurus Labs, as its listed peers. They are currently trading at a P/E of 57.9, 76.4, 169.0, and 90.2 (as of Aug. 20, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.

Symbiotec Pharmalab Ltd. (SPL) is a research and development-driven, science-based pharmaceutical and biotechnology company with capabilities across three platforms- organic chemistry, biotechnology and complex injectables. It has a global leadership position in corticosteroid and steroidal-hormone active pharmaceutical ingredients (“APIs”) in volume terms in Fiscal 2026, with a global volume market share of 38.2% in corticosteroid and 23.8% in steroidal-hormone APIs (excluding androstenedione and hydroxyprogesterone caproate). (Source: F&S Report)
It is the only Indian and global company to have a presence across the top 10 corticosteroid and steroidal-hormone APIs in Fiscal 2026, (Source: F&S Report) demonstrating the depth of its portfolio. The company manufactures these products using fermentation and multi-step complex chemical reactions. With over 30 years of industry experience, it has evolved from a lab scale steroidal-hormone API manufacturer in 1995 into an industrial-scale, backward-integrated platform with approvals from the United States Food and Drug Administration (“US FDA”), European Union Good Manufacturing Practices (“EU-GMP”), Ministry of Food and Drug Safety, Korea and other global organizations.
The company has leveraged its deep capabilities across organic chemistry, biotechnology, and complex injectables to operate as a contract development and manufacturing organization (“CDMO”) variably for specialty pharmaceutical and nutraceutical companies globally, offering products and services across the three platforms in which it also manufactures its own products. As of March 31, 2026, SPL had two operational industrial-scale API manufacturing facilities with a maximum chemical synthesis capacity of 584.67 metric tonnes (“MT”), fermentation capacity of 300 kiloliters (“KL”). Further, it has commissioned two additional manufacturing facilities at Ujjain, Madhya Pradesh and Mhow, Madhya Pradesh, leading to an aggregate maximum chemical synthesis capacity of 584.67 MT, maximum fermentation capacity of 700 KL, and complex injectables capacity of 20 million vials per annum, enabling it to function as a vertically integrated ‘microbe-to-pharmacy’ and ‘farm-to-pharmacy’ platform with cost-efficient operations.
Its biotechnology facilities are equipped with fermenters of 5 KL, 35 KL and 100 KL, providing it flexibility in the scale of operations. Further, the company is in the process of expanding its biologics capacity by adding a proposed dedicated 14 KL (comprising two reactors of 7 KL each) fermentation capacity for biologics manufacturing in Ujjain, Madhya Pradesh. It has demonstrated agility by rapidly embracing technologies such as biotransformation, precision fermentation, double chamber platforms, continuous flow chemistry and integrating them into its manufacturing processes, whichit believes has enabled the company to bring complex products to the market. It has also consistently invested in scaling capacity and infrastructure, which has allowed it to compete effectively with larger global players and address expanding demand. Finally, its commitment to maintaining compliance requirements across regulated markets distinguishes it, and its global quality standards enable it to service pharmaceutical innovators and generics across highly regulated markets, while benefitting from price advantages of its manufacturing operations in Asia.
SPL has a robust product portfolio of over 60 corticosteroid and steroidal-hormone APIs that are supplied globally, including Hydrocortisones, Betamethasones, Methylprednisolones, Progesterones, Estrogens and Testosterones, which are used extensively in critical care setups, as well as across chronic therapeutic areas such as respiratory, dermatology, pain management, oncology and gynecology. In molecules such as Hydrocortisone, Testosterone and Methylprednisolone, it holds a global leadership position, capturing over 50% market share of supply by volume, with market shares of 80.1%, 76.4% and 76.0% respectively, in Fiscal 2026. (Source: F&S Report). As of March 31, 2026, it holds 43 drug master files (“DMFs”) registered with the US FDA and 23 certificates of suitability (“CEPs”) from the European Directorate for the Quality of Medicines and HealthCare (“EDQM”).
Its capabilities span three interlinked platforms: (i) organic chemistry, including flow chemistry, hydrogenation, and photochemistry; (ii) biotechnology, including biosynthesis and biotransformation, and recombinant biologics, including Glucagon-like Peptide-1 (“GLP-1”) and Insulins; and (iii) forward integration into complex injectables including double-chamber vials, double-chamber bags and double-chamber syringes, collectively enabling it to commercialize and scale hard-to-replicate products and services. Its differentiated chemistry capabilities enable it to manufacture APIs and products with up to 400 synthesis steps validated under cGMP efficiently. Its ability to develop and scale niche, complex API products is reflected in its success in developing conjugated estrogen products, where SPL is one of the few companies globally to have successfully developed a complex API with 82 US FDA mandated components despite the product’s primary composition patents having expired several decades prior. (Source: F&S Report)
SPL’s broad capabilities are enabled by conversion of commodity plant-based derivative inputs (farm/ microbe-to- pharmacy approach) and work with diverse microbial strains such as bacteria, fungi, yeast and algae to convert into high value steroid and hormonal pre-cursors. This supports backward integration and underpins its ‘farm/microbe-to-pharmacy’ approach. This integration allows it to make strategic, cost-effective ‘make versus buy’ decisions for key starting materials (“KSMs”) for over 80% of its products by revenue, thereby reducing external dependence for sourcing intermediates from other geographies. The company is among the few backward-integrated Indian and global manufacturers capable of producing in-house corticosteroid and hormone precursors, as of March 31, 2026. (Source: F&S Report).
As of March 31, 2026, it had three complementary verticals, through which it had variably supplied products to over 200 customers in over 40 countries, including leading generic and specialty pharmaceutical companies in the United States, Europe, and Asia – (i) API products, (ii) CDMO services, and (iii) complex injectables. Its research and development (“R&D”) efforts are central to its ability to build, scale, and sustain complex manufacturing technologies. As of March 31, 2026, its R&D team comprised 156 scientists and engineers, including 117 with master’s degrees and 10 with PhDs, engaged in new product development, process innovation, technology transfer and scale-up.
As of March 31, 2026, it operated three dedicated R&D centres in Indore, Madhya Pradesh, focused on driving innovation across organic chemistry, biotechnology and complex injectables. SPL’s commitment to innovation is demonstrated by its investment of 3.42%, 4.14%, 2.86% of revenue from operations into R&D in Fiscals 2026, 2025 and 2024, respectively. As of March 31, 2026, it had a consolidated workforce of over 2,500 employees, including both permanent and contractual staff, providing scale and flexibility across its operations.
Merchant Banker's Track Record
The four BRLMs associated with this issue has handled 83 IPOs in the last three fiscals out of which 26 issues closed below the issue price on the listing date.
Conclusion
SPL is a global leader as a research and development driven, science based pharmaceutical and biotechnology company across major platforms. It marked progress in its top lines for the reported periods, but marked minor setback for FY25, following accounting adjustments. The company has expanded its capacities and that will start contributing soon to its top and bottom lines. Based on its recent financial data, the issue appears fully priced. Well-informed investors can park funds for medium to long term rewards.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.