Priority Jewels IPO Review – Only Well-Informed/Cash Surplus/Risk Seekers May Park Moderate Funds for Medium Term
Issue Details / Capital History
The company is coming out with its maiden book building route IPO of 4575000 equity shares (worth Rs. 91.50 cr. at the upper cap). The company has announced a price band of Rs. 190 – Rs. 200 per equity shares of Rs. 10 each. The issue opens for subscription on August 28, 2026, and will close on September 01, 2026. The minimum application to be made is for 75 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 25.42% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 75.00 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes.
The issue is solely lead managed by Mefcom Capital Markets Ltd., while MUFG Intime India Pvt. Ltd., is the registrar to the issue. Mefcom Securities Ltd. is a syndicate member.
After issuing/converting initial equity shares at par value, the company has issued further equity shares at a fixed price of Rs. 190.00 per share in February 2026. It has also issued bonus shares in the ratio of 3 for 1 in February 2025. The average cost of acquisition of shares by the promoters is Rs. NIL, Rs. 0.00, Rs. 1.20, Rs. 2.26, Rs. 2.50, and Rs. 82.00 per share.
Post-IPO, its current paid-up equity capital of Rs. 13.43 cr. (13425000 equity shares) will stand enhanced to Rs. 18.00 cr. (18000000 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 360.00 cr.
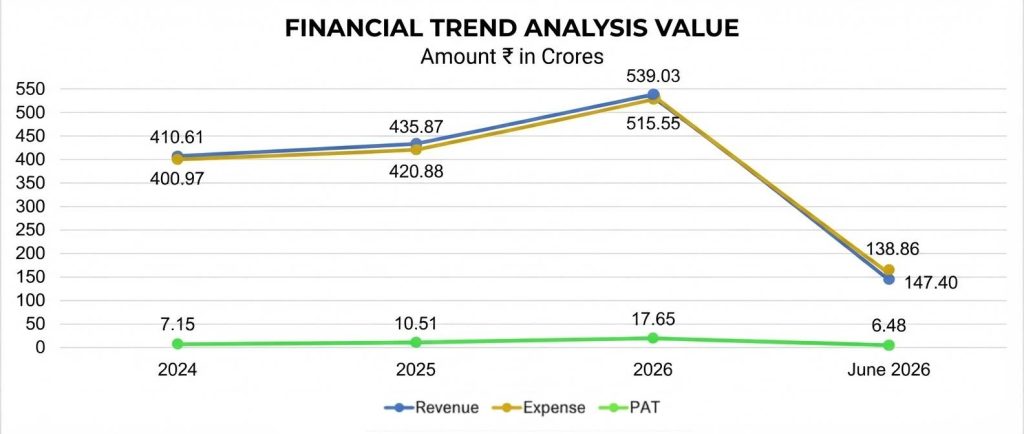
On the financial performance front, for the last three fiscals, the company has posted a total revenue/net profit, of Rs. 410.61 cr. / Rs. 7.15 cr. (FY24), Rs. 435.87 cr. / Rs. 10.51 cr. (FY25), and Rs. 539.03 cr. / Rs. 17.65 cr. (FY26). For Q1 of FY26, it has earned a net profit of Rs. 6.48 cr. on a total revenue of Rs. 147.40 cr. The company posted steady growth in its top and bottom lines for the reported periods. However, surging Trade Receivables, year-on-year as well as its contingent liabilities of Rs. 6.06 cr. as of June 30, 2026, raise alarm.
For the last three fiscals, the company has posted an average EPS of Rs. 10.74 and an average RoNW of 10.96 %. The issue is priced at a P/BV of 1.84 based on its NAV of Rs. 108.59 as of June 30, 2026, and at a P/BV of 1.56 based on its post-IPO NAV of Rs. 127.88 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 13.90. Based on FY25 earnings, the P/E stands at 20.39. The issue appears aggressively priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 1.74% (FY24), 2.41% (FY25), 3.27% (FY26), 4.39% (Q1-FY27), and RoCE margins of 17.47%, 22.36%, 25.36%, 6.92% respectively, for the referred periods.
All amounts in Indian Rupees crores
Dividend Policy
The company has not paid any dividends for the reported periods of the offer document. It has already adopted a dividend policy in April 2025, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Khazanchi Jewellers, RBZ Jewellers, Ashapuri Gold, as its listed peers. They are currently trading at a P/E of 19.2, 10.0, and 6.42 (as of Aug. 25, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash. This comparison appears to be an eyewash.

Priority Jewels Ltd. (PJL) is engaged in designing, manufacturing and sale of a wide range of light-weight, affordable diamond-studded gold and platinum fine jewellery. The company sells directly to independent jewellers and jewellery chains in India as well as select international markets. It supplies products to jewellery chains, including CaratLane Trading Private Limited, Kalyan Jewellers India Limited, Reliance Retail Limited, Malabar Gold & Diamonds FZCO, Tribhovandas Bhimji Zaveri Limited and Senco Gold Limited.
Its ability to blend craftsmanship with innovation has enabled the company to establish long-standing relationships with major Indian retail jewellery players, reinforcing its position as a trusted supplier to customers (Source: CARE Report). PJL’s manufacturing process begins with designing and then involves rapid prototyping, model making, mould making, waxing, casting, sprue grinding, filing, polishing, stone setting, final polishing, rhodium plating, and quality control. Its portfolio primarily comprises daily wear jewellery, including rings, earrings, pendants, neckwear, bracelets and occasion couture jewellery, all of which are developed using contemporary design approaches and modern manufacturing techniques.
The company also manufactures lab-grown diamond jewellery based on specific orders received from customers. Its product portfolio is centred on light-weight, affordable, daily wear pieces that are crafted for a wide audience across the country. By focusing on innovative designs, modern aesthetics and functionality, PJL uniquely positions its offerings to target growing demand from a diverse consumer base with rising disposable incomes and preferences for designer jewellery that reflect both style and practicality.
As of June 30, 2026, it has over 200 customers, predominantly in India, including 125 independent jewellers and 53 jewellery chains. Several of the independent jewellers and jewellery chains it serves are long-standing customers. Over the years, the company has expanded market presence across 21 states and 3 union territories in India and have exported products to 13 countries globally, including the United States of America, UAE, Hong Kong and Norway. Most of its exports are to overseas stores of Indian jewellery chains, primarily catering to the Indian diaspora.
PJL’s strategic focus on the light weight, affordable diamond-studded jewellery segment and industry expertise positions it well to capitalize on recent trends and growth opportunities in the Indian jewellery market. The Indian gems and jewellery wholesale market is expected to grow at a CAGR of 14.45% between CY25 and CY30. In particular, domestic demand is fueled by rising disposable incomes, urbanization, and a rising demand for branded jewellery, increasing adoption of lightweight and studded jewellery, expanding omnichannel retail presence, favorable demographics, and sustained demand from weddings and festive occasions, supported by continued formalization of the industry.
Further, according to a report by the World Gold Council, recent interactions between Metals Focus and retailers have highlighted a significant increase in demand for lightweight jewellery, especially in the daily wear jewellery segment, including fashionable and fast-moving designs. It has established two jewellery manufacturing facilities in India that cater to domestic and export sales. As of June 30, 2026, it had 211 employees on its payroll.
Merchant Banker's Track Record
The BRLM associated with this offer has handled 1 issue in the ongoing fiscal, and the only listing took place was closed above the offer price on listing date.
Conclusion
PJL is engaged in the light-weight, affordable diamond studded gold and platinum jewellery. It serves over 200 customers across the global markets, and has marquee customers. The company posted growth in its top and bottom lines for the reported periods. Rising Trade Receivables, year-on-year, raise concerns. Based on its recent average financial data, the issue appears aggressively priced. Only well-informed/cash surplus/risk seekers may park moderate funds for medium term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.