Pramodini Medicare IPO Review (NSE SME)
Pramodini Medicare Ltd. (PML) is a diagnostic service provider in India. It provides a range of technology-enabled diagnostic services such as radiology, clinical laboratory and nuclear medicine service to public hospitals, private hospitals, certain PSU (Public Sector Undertaking) of Government of India and medical colleges across tier I, tier II and tier III cities throughout India. Its diagnostic services include a comprehensive range of offerings: (i) “Radiology” which covers Magnetic Resonance Imaging (MRI), Computed Tomography (CT scan), X- ray, Ultrasound with colour doppler, Mammography, Dexa Scan and Intervention Radiology, (ii) “Clinical Laboratory” which includes Haematology, Micro-Biology, Immunology, Pathology & Bio-Chemistry and (iii) “Nuclear Medicine” which includes PET-CT (Positron Emission Tomography-Computed Tomography), SPECT (Single Photon Emission Computed Tomography) and Nuclear therapy.
The company also provides teleradiology services through its registered office situated at Vijayawada which functions on a 24×7 basis throughout the year. It provides healthcare services for core testing, patients diagnosis, disease prevention and monitoring of various health conditions. Its services includes both routine and specialized tests, which are used for prediction, early detection, diagnostic screening, confirmation and/or monitoring of diseases. PML’s business operates across four key models namely 1. Public Private Partnership (with government hospitals and government teaching hospitals) 2. Private Partnership (with private sector hospitals) 3. Strategic Partnership with PSUs (Public Sector Undertakings) Government of India and 4. Private Centres (standalone centre).
The above models are based on hospital partnerships, where diagnostic centres are set up within the existing premises of hospitals, health centres and it supports them by providing diagnostic testing service. It has entered into Memorandum of Understanding (MOUs) with these institutions for the establishment and operation of onsite diagnostic centres within their existing healthcare facilities. As on the date of filing of this Red Herring Prospectus, it is operating through 16 diagnostic centres across these different models. These centres are located in 7 states in India: Uttar Pradesh, Andhra Pradesh, Karnataka, West Bengal, Haryana/NCR Delhi, Madhya Pradesh and Kerala (Operation yet to commence). The services offered at each location vary based on the scope agreed under the respective MOUs. It has presence across 14 cities in India. The company also has a processing unit cum laboratory in Vijayawada.
PML offers a one-stop solution for all services to patients through its operational network. The company also offers customized health and wellness packages tailored to meet the specific requirements of patients. It focuses on a patient centric approach to enhance the overall quality of services for optimal patient’s satisfaction. Several factors, including integrated services model, quality of diagnostic services, centre infrastructure and patient’s experience, convenience of its operational network in its core geographies are important differentiating factors in patients choosing it as their preferred and trusted diagnostic service provider, which helps the company in retaining its patients, and sets it apart from competitors. As of March 31, 2026, it had 161 employees on its payroll and additional 18 contract workers.

Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO of 5851200 equity shares of Rs. 10 each to mobilize Rs 69.04 cr. at the upper cap. The IPO consists of 5350800 fresh equity shares (worth Rs. 63.14 cr. at the upper cap), and an Offer for Sale (OFS) of 500400 equity shares (worth Rs. 5.90 cr. at the upper cap). The company has announced a price band of Rs. 110 - Rs. 118 per share. The minimum application to be made is for 2400 shares and in multiples of 1200 shares thereon, thereafter. The IPO opens for subscription on August 12, 2026, and will close on August 14, 2026. The IPO constitute 26.54% of the post-IPO paid-up capital of the company. The shares will be listed on NSE SME Emerge. From the net proceeds of the fresh equity issue, it will utilize Rs. 45.15 cr. for capex on purchase of medical equipments, and the rest for general corporate purposes.
The IPO is solely lead managed by Smart Horizon Capital Advisors Pvt. Ltd., while Purva Sharegistry (India)Pvt. Ltd., is the registrar to the issue. Shreni Shares Ltd., and Rainbow Securities Pvt. Ltd. are the market makers. Shreni Shares Ltd. is also a syndicate member.
After issuing initial equity capital at par value, the company issued further shares in the price range of Rs. 110.00 – Rs. 155.00 per share, between March 2023, and August 2023. It has also issued bonus shares in the ratio of 12 for 1 in March 2026. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. NA, but as shown on page 1 of RHP, it stands at Rs. 4.25, Rs. 6.23, and Rs. 6.99 per share.
Post-IPO, company’s current paid-up equity capital of Rs. 16.69 cr. will stand enhanced to Rs. 22.05 cr. Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 260.14 cr.
IPO Lead Managers & Registrar
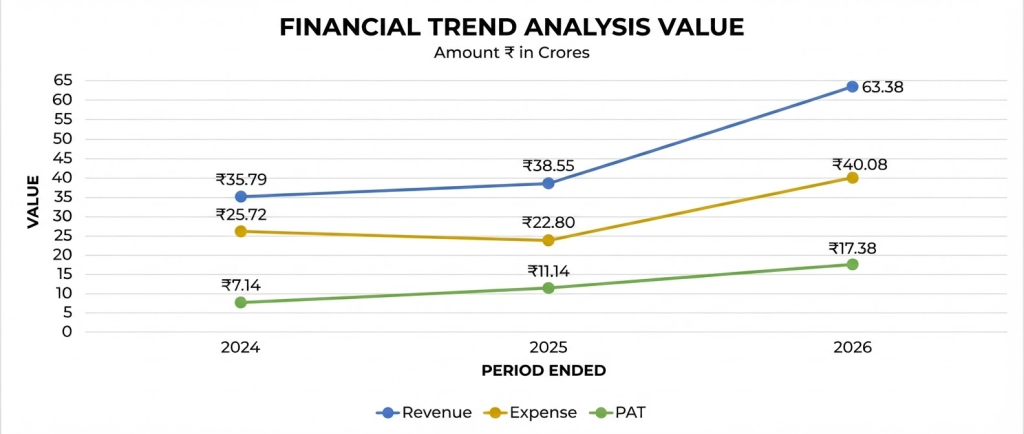
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) reported a total income/net profit of Rs. 35.79 cr. / Rs. 7.14 cr. (FY24), Rs. 38.55 cr. / Rs. 11.14 cr. (FY25), and Rs. 63.38 cr. / Rs. 17.38 cr. (FY26). It marked growth in its top and bottom lines for the reported periods. However, the PAT margins raise eyebrows and concern over its sustainability going forward as it is operating in a highly competitive and fragmented segment. Its outperforming margins compared to its listed peers also raise eyebrows.
For the last three fiscals, the company has reported an average EPS of Rs. 8.15, and an average RoNW of 31.29%. The issue is priced at a P/BV of 3.71 based on its NAV of Rs. 31.84 per share as of March 31, 2026, but its post-IPO NAV data is missing from the offer documents.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 14.97, and based on FY25 earnings, the P/E stands at 23.37. The issue appears aggressively priced, based on its average earnings.
For the reported periods, the company has posted PAT margins of 19.67% (FY24), 28.84% (FY25), 27.90% (FY26), and RoCE margins of 31.90%, 36.48%, 34.66%, respectively, for referred periods.
All amounts in Indian Rupees crores
The company has not paid any dividend for the reported periods of the offer document. It will adopt a prudent dividend policy, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Invicta Diagnostics, Krsnaa Diagnostics, Star Imaging, as its listed peers. They are currently trading at a P/E of 19.9, 17.8, and 7.37 (as of August 10, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Merchant Banker's Track Record
On merchant banker’s track record aspect, this is the 1st mandate form LSI Financial Services, while this is 6th mandate from NexGen Financial in the last two fiscals (including the ongoing one). Out of last 5 listings, 1 listed at discount and the rest with premium ranging from 2.56% to 67.68% on the listing date.
Conclusion
PML is engaged in providing diagnostic services in India, currently having presence in 7 states. The company marked growth in its top and bottom lines for the reported periods. Its outperforming margins compared to listed peers for the last three fiscals raise concern over its sustainability going forward, as it is operating in a highly competitive and fragmented segments. Based on its recent super financial data, the issue appears aggressively priced. Only well-informed/cash surplus investors may park moderate funds for long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.