SFC Environmental IPO Review – Well-informed Investors May Park Funds for Medium to Long Term
Issue Details / Capital History
The company is coming out with its maiden book building route secondary IPO of 20228205 equity shares worth Rs. 667.53 cr. at the upper cap. The IPO consists of fresh equity shares worth Rs. 150 cr. (approx. 4545455 equity shares at the upper cap), and an Offer for Sale (OFS) of 15682750 equity shares (worth Rs. 517.53 cr.at the upper cap). The company has announced a price band of Rs. 313 – Rs. 330 per equity shares of Rs. 2 each. The issue opens for subscription on October 27, 2026, and will close on October 29, 2026. The minimum application to be made is for 45 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 20.65% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 42.23 cr. for pre-payment of certain borrowings, Rs. 74.92 cr. for working capital, and the rest for general corporate purposes.
The joint Book Running Lead Managers (BRLMs) to this issue are IIFL Capital Services Ltd., JM Financial Ltd., and Nuvama Wealth Management Ltd., while MUFG Intime India Pvt. Ltd. is the registrar to the issue. JM Financial Services Ltd., and Nuvama Wealth Management Ltd., are syndicate members.
Having issued/converted initial equity shares at par value, the company has issued further equity shares at a fixed price of Rs. 4.60 per share (based on Rs. 2 FV), in March 2008. The company also issued bonus shares in the ratio of 2 for 1 in September 2024. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 36.72, and Rs. 42.85 per share.
Post-IPO, its current paid-up equity capital of Rs. 18.68 cr. (93411270 equity shares) will stand enhanced to Rs. 19.59 cr. (97956724 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 3232.57 cr.
On the financial performance front, for the last three fiscals, the company has posted a total income/net profit, of Rs. 676.74 cr. / Rs. 144.17 cr. (FY24), Rs. 726.93 cr. / Rs. 152.01 cr. (FY25), and Rs. 821.27 cr. / Rs. 160.21 cr. (FY26). ForQ1 of FY27 ended on June 30, 2026, it earned a net profit of Rs. 1.48 cr. on a total income of Rs. 137.90 r. The company posted growth in its performances for the reported periods. According to the management, the company has business seasonality, as its 60+% business comes in second half as per historical trends.
For the last three fiscals, the company has posted an average EPS of Rs. 15.93 and an average RoNW of 23.82 %. The issue is priced at a P/BV of 3.83 based on its NAV of Rs. 86.23 as of June 30, 2026, and at a P/BV of 3.38 based on its post-IPO NAV of Rs. 97.54 per share at the upper cap.
If we attribute FY27 annualized earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 540.98. Based on FY26 earnings, the P/E stands at 20.17. The issue appears aggressively priced based on its recent average performance. According to the management, since their business is cyclical and most of the project’s implementation happens only in the second half. Thus, any evaluation based on Q1 performance will not give real picture. Its total revenue has 90+% share from repeat orders and as of June 30, 2026, SETL ‘s orderbook stood at Rs. 1570+ cr. Indicating strong pipeline of orders. If we consider full years impact, the issue appears fully priced.
For the reported periods, the company has reported PAT Margins of 21.93% (FY24), 21.78% (FY25), 19.94% (FY26), 1.11% (Q1-FY27), and RoCE margins of 28.56%, 29.29%, 22.21%, 0.72%, respectively, for the referred periods.
The company has paid a dividend of 150% (FY24), 166.67% (FY25), 150% (FY27). It has adopted a dividend policy in August 2024, based on its earnings and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Thermax Ltd., Praj Ind. Ltd., Ion Exchange, as its listed peers. They are currently trading at a P/E of 67.1, 91.4, and 45.0 (as of October 23 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
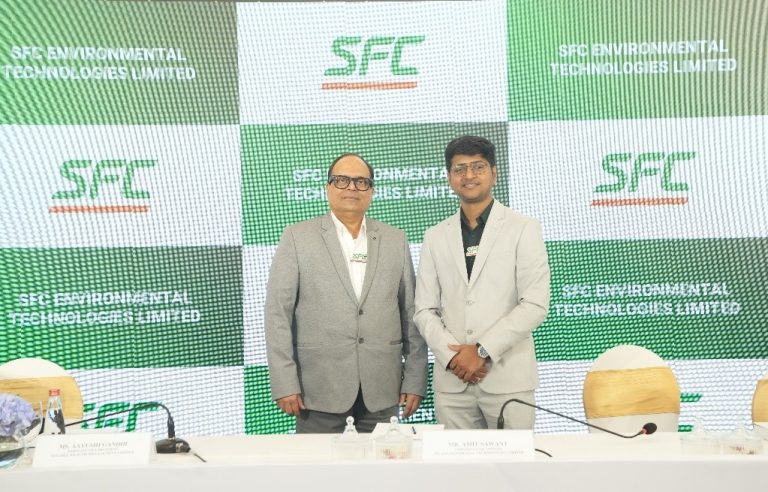
SFC Environmental Technologies Ltd. (SETL) is an environmental technology company offering efficient technologies and comprehensive engineering solutions in the field of wastewater treatment (“WWT”), wastewater recycling & reuse (“WRR”) and solid waste treatment (“SWT”). Its core operations include providing design, technology, manufacturing, supply and supervision for installation and commissioning of equipment for the treatment of wastewater. Its proprietary technology for wastewater treatment is C-Tech, which is an advanced technology for treating sewage and effluents. (Source: F&S Report)
With 728 installations commissioned in the WWT segment, as of July 31, 2026, particularly in sewage treatment plants (“STPs”), the company holds over 80% market share in sequencing batch reactor (“SBR”) technology, a key wastewater treatment method in India. (Source: F&S Report) SETL’s technologies facilitate the treatment of 17,511.11 million liters per day (“MLD”) of wastewater, as of July 31, 2026. (Source: F&S Report).
Company’s SBR technology: C-Tech has been implemented in the large-scale SBR-based STPs in India, including one of the largest STP under development, which has a treatment capacity of 424 MLD wastewater, as of July 31, 2026. (Source: F&S Report) In addition to its C-Tech package, the company offers high-efficiency turbo blowers for aeration in wastewater treatment, fibre disc filters for efficient removal of suspended solids from wastewater and solar sludge drying systems to efficiently dry sludge from wastewater and solid waste treatment using solar energy. Additionally, it has entered into an exclusive supply agreement with DSP Singapore Holdings Pte Ltd (“DuPont”) in August 2024 along with an amendment agreement in June 2025 for membrane aerated biofilm reactor technology (OXYFAS & OXYFILM), which are used to enhance efficiency and capacity of existing wastewater treatment plant, particularly for overloaded or outdated facilities.
Building on its secondary wastewater treatment capabilities, the company has recently expanded into tertiary treatment solutions. Its wastewater recycling and reuse offerings include design, engineering, manufacturing, procuring, supply, installation and commissioning of projects / plants based on ultrafiltration (UF), closed circuit reverse osmosis (CCRO), and membrane bioreactor technologies (MBR). It has entered into an exclusive supply agreement with DSP Singapore Holdings Pte Ltd (“DuPont”) for the exclusive distribution in India of certain WRR components in the municipal wastewater treatment plants market viz.: (i) membranes for submerged UF (Modules L20N V2 & S10N V2), (ii) CCRO technology, and (iii) B50N MBR modules (MBR).
Leveraging its established leadership and distribution network in WWT and an exclusive supply arrangement with DuPont, the company has expanded into the WRR segment as an extension of its core business. The WRR segment is expected to witness significant growth, driven by increasing water scarcity and government initiatives focused on water conservation in India. (Source: F&S Report) Following SETL’s expansion into the WRR segment, its order book for the WRR segment stood at Rs. 561.07 cr. as on August 31, 2026. As on the date of this Red Herring Prospectus, the Company has obtained registration for its trademark “C-TECH” in the European Union and in Vietnam.
In India, the compressed biogas (“CBG”) blending obligation mandates oil marketing companies to blend CBG into their fuel infrastructure and mandates the OGMCs to set up projects for CBG production from organic waste and biomass. (Source: F&S Report) Towards this initiative, through its wholly-owned subsidiary, HWTPL, it has secured orders from a government-owned oil company for the engineering, procurement, commissioning and operation & maintenance for a period of 10 years, of: (i) a 125 TPD unsegregated MSW based compressed biogas (CBG) plant for commercial use at Tinsukia, Assam in April 2025; and (ii) a 300 TPD segregated MSW based compressed biogas plant for commercial use at Bhubaneswar, Odisha in May 2025. As of June 30, 2026, the company had an order book worth Rs. 1570+ cr. As of August 31, 2026, it had 264 employees on its payroll.

Merchant Banker's Track Record
The three BRLMs associated with this issue have handled 111 public issues in the past three fiscals, out of which 35 issues closed below the offer price on listing date.
Conclusion
SETL specializes in waste water treatment with latest technology. Its order book stood at Rs.1570+ cr., as of June 30, 2026. Its overall revenue consists of over 90% repeat orders. Management clarified that, as its business has seasonality, Q1-FY27 performance not indicating the real picture. Based on its recent average financial data, the issue appears fully priced. Well-informed investors may park funds for medium to long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.