LAPL Automotive IPO Review (BSE SME)
LAPL Automotive Ltd. (LAL) is an integrated automotive components manufacturer operating across ODM (Original Design Manufacturing) and OBM (Original Brand Manufacturing) models, with a diversified product portfolio spanning automotive lighting systems, mirrors, and plastic moulded components. The Company caters to automobile OEMs across passenger vehicles, commercial vehicles, two-wheelers, and electric mobility segments. With a diversified product portfolio, the company caters to the products of tail lamps, front and rear indicators, reflex reflectors, head lamp, stop lamp, position lamp, reverse lamp and roof lamp, etc., the motor segments cover starter motor, wiper motor, rotors etc. and other components and accessories segment such as hood, stators, small BLDC fans and many more for various spectrum of vehicles.
It is an IATF 16949:2016 certified company, providing customized lighting solutions for various vehicle segments. Its lighting products are designed using technologies such as light-emitting diode (“LED”). The Company has an in-house testing facility for quality testing and assurance, where products undergo various environmental testing parameters which includes humidity, tensile strength, heat, freeze, flammability, voltage control tests, endurance and drop test, etc. to cater AIS (Automotive Indian Standards). Some of its products are also certified by other approved certifying agencies such as CIRT, ICAT, VRDEA and ARAI for safety standards and quality assurance as required by few of its customers prior to its supply. It improves quality control, product reliability, faster testing, quicker product development, customization and increased customer satisfaction.
The Company operates as an Original Design Manufacturer (“ODM”) and Original Brand Manufacturer (“OBM”) under its proprietary brand, “LAPL.” Through these complementary business verticals, it leverages design expertise, manufacturing capabilities, and market understanding to serve a diverse customer base while strengthening its brand presence. Under the ODM vertical, LAL designs and manufactures automotive components for customers who market these products under their own brands or integrate them into vehicle production. Company’s three manufacturing units located in Aurangabad, Maharashtra, ensure that products consistently meet prescribed quality standards while adhering to the specific technical and performance requirements of its clients. This model enables it to combine innovation with strong in-house capabilities to deliver customized solutions to automotive component suppliers and vehicle manufacturers.
Under the OBM vertical, it designs, manufactures, and supplies automotive components under its own brand, “LAPL,” allowing it to build brand recognition and establish a direct connection with the market. This approach provides it with end-to-end control over the value chain, encompassing design and engineering, manufacturing, branding, marketing, and sales. The OBM segment supports its strategic objective of enhancing brand equity while expanding presence in the automotive components industry. Its ODM business contributed around 77% of its top line and the rest by OBM business. As of June 30, 2026, it had 208 employees on its payroll (including 135 contract labourers).

Issue Details / Capital History
The company is coming out with its maiden book building route IPO of 3446400 equity shares of Rs. 10 each to mobilize Rs. 32.40 cr. at the upper cap. The company has announced the price band of Rs. 88 – Rs. 94 per share. The minimum application to be made is for 2400 shares and in multiples of 1200 shares thereon, thereafter. The issue opens for subscription on August 06, 2026 and will close on August 10, 2026. The shares will be listed on BSE SME. The IPO constitute 27.49% of the post-IPO paid-up capital of the company. From the net proceeds, the company will utilize Rs. 4.79 cr. for repayment/prepayment of certain borrowings, Rs. 19.56 cr. for capex on setting up of a new manufacturing facility, and the rest for general corporate purposes.
The IPO is solely lead managed by GYR Capital Advisors Pvt. Ltd., and Maashitla Securities Pvt. Ltd. is the registrar to the issue. Giriraj Stock Broking Pvt. Ltd., and Mansi Share and Stock Broking Pvt. Ltd. are the market makers. GYR Capital Advisors is also a syndicate member.
After issuing initial equity capital at par, the company issued further shares in the price range of Rs. 18.50 - Rs. 116.00 between March 2015, and May 2026. It has also issued bonus shares in the ratio of 1 for 1 in March 2007, 1 for 2 in April 2011, 1 for 2 in March 2016, and 7 for 4 in December 2024. The average cost of acquision of shares by the promoters is Rs. 3.18, Rs. 3.23, Rs. 3.27 per share.
Post-IPO, company’s current paid-up equity capital of Rs. 9.09 cr. will stand enhanced to Rs. 12.54 cr. Based on the upper band of the IPO pricing, the company is looking for a market cap of Rs. 117.84 cr.
IPO Lead Managers & Registrar
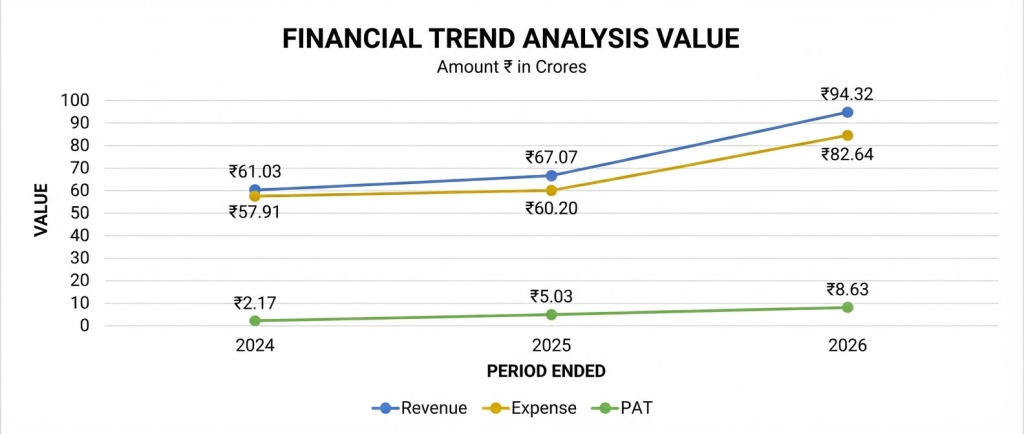
On the financial performance front, for the last three fiscals, the company has posted total income/ net profit, of Rs. 61.03 cr. / Rs. 2.17 cr. (FY24), Rs. 67.07 cr. / Rs. 5.03 cr. (FY25), Rs. 94.31 cr. / Rs. 8.63 cr. (FY26). Boosted performance in a pre-IPO year raise eyebrows, and concern over its sustainability as the company is operating in a highly competitive and fragmented segment. Rising trade receivables year-on-year raise alarm.
For the last three fiscals, the company has reported an average EPS of Rs. 7.22 and an average RoNW of 30.30%. The issue is priced at a P/BV of 3.28 based on its NAV of Rs. 28.70 per share as of March 31, 2026, but its post-IPO NAV data is missing from the offer documents.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at a P/E of 13.66, and based on FY25 earnings, the P/E stands at 23.38. The issue appears fully priced based on its earnings.
The company has posted PAT Margins of 3.58% (FY24), 7.63% (FY25), 9.25% (FY26), and RoCE margins of 21.65%, 30.85%, 34.37%, respectively for referred periods.
All amounts in Indian Rupees crores
The company has not paid any dividends for the reported periods of the offer documents. It has adopted a dividend policy in March 2026, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has no listed peers to compare has shown Minda Corp., and Fiem Ind. as its listed peers. They are currently trading at a P/E of 49.0 and 24.0 (as of August 03, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.
Merchant Banker's Track Record
This is the 40th mandate from GYR Capital Advisors in the last three fiscals (including the ongoing one). Out of the last 11 listings, 1 opened at par and the rest with premium ranging from 4.92% to 90.00% on the listing date.
Conclusion
LAL is an integrated automotive components manufacturer operating across ODM and OBM models. The company posted growth in its top and bottom lines for the reported periods. Quantum jump in its bottom lines from FY25 onwards raise eyebrows and concern over its sustainability as it is operating in a highly competitive and fragmented segment. Based on its recent financial data, the issue appears fully priced. Only well-informed/cash surplus investors may park moderate funds for medium term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.