Lumino Industries IPO Review – Well-Informed Investors can Park Funds for Medium to Long Term
Issue Details / Capital History
The company is coming out with its maiden book building route combo IPO of worth Rs. 700 cr. (approx. 85365854 equity shares, at the upper cap). The IPO consists of fresh equity shares issue worth Rs. 500 cr. (approx. 60975610 equity shares at the upper cap), and an Offer for Sale (OFS) worth Rs. 200 cr. (Approx. 24390244 equity shares at the upper cap). The company has announced a price band of Rs. 78 – Rs. 82 per equity shares of Rs. 5 each. The issue opens for subscription on August 27, 2026, and will close on August 31, 2026. The minimum application to be made is for 182 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 28.03% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 337.00 cr. for repayment/prepayment of certain borrowings, Rs. 15.01 cr. for capex on purchase of equipment, machinery, civil work on existing manufacturing facility, and the rest for general corporate purposes.
The company has reserved equity shares worth Rs. 10.00 cr. (approx. 1219512 equity shares at the upper cap) for its eligible employees. From the rest, it has allocated note more than 50% for QIBs, not less than 15% for HNIs and not less than 35% for Retail investors.
The three joint Book Running Lead Managers (BRLMs) to this issue are Motilal Oswal Investment Advisors Ltd., JM Financial Ltd., Monarch Networth Capital Ltd., while Bigshare Services Pvt. Ltd., is the registrar to the issue. Motilal Oswal Financial Services Ltd., JM Financial Services Ltd., Monarch Networth Capital Ltd., are the syndicate members.
After issuing/converting initial equity shares at par value, the company has issued further equity shares at a fixed price of Rs. 250 per share (on the basis of Rs. 5 FV), between March 2011, and March 2012. It has also issued bonus shares in the ratio of 1 for 5 in May 2007, 2 for 3 in October 2022, and 3 for 1 in November 2024. The average cost of acquisition of shares by the promoters is Rs. NIL, and Rs. 0.002 per share.
Post-IPO, its current paid-up equity capital of Rs. 121.79 cr. (243578096 equity shares) will stand enhanced to Rs. 152.28 cr. (304553706 equity shares). Based on the upper cap of the price band, the company is looking for a market cap of Rs. 2497.34 cr.
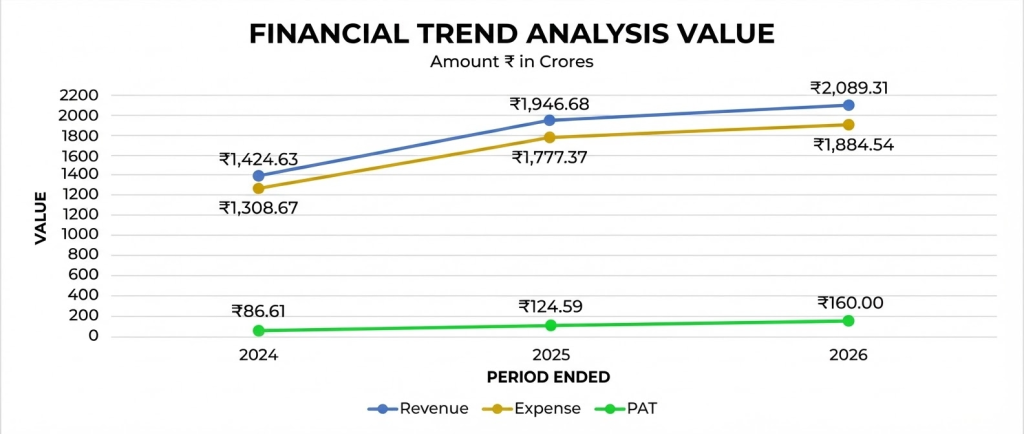
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit, of Rs. 1424.63 cr. / Rs. 86.61 cr. (FY24), Rs. 1946.68 cr. / Rs. 124.59 cr. (FY25), and Rs. 2089.31 cr. / Rs. 160.00 cr. (FY26). The company posted steady growth in its top and bottom lines for the reported periods. However, surging Trade Receivables, year-on-year as well as its contingent liabilities of Rs. 24.86 cr. as of March 31, 2026, raise alarm.
For the last three fiscals, the company has posted an average EPS of Rs. 5.58 and an average RoNW of 24.07 %. The issue is priced at a P/BV of 2.74 based on its NAV of Rs. 29.95 as of March 31, 2026, and at a P/BV of 2.03 based on its post-IPO NAV of Rs. 40.37 per share at the upper cap.
If we attribute FY26 super earnings to its post-IPO fully diluted paid-up equity capital, then the asking price is at P/E of 15.62. Based on FY25 earnings, the P/E stands at 20.05. The issue appears fully priced based on its recent average performance.
For the reported periods, the company has reported PAT Margins of 6.08% (FY24), 6.40% (FY25), 7.66% (FY26), and RoCE margins of 32.27%, 31.89%, 25.75%, respectively, for the referred periods.
All amounts in Indian Rupees crores
Dividend Policy
The company has not paid any dividends for the reported periods of the offer document. It has already adopted a dividend policy in December 2024, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has shown Apar Ind., Bajel Proj., Kalpataru Proj., KEC Intl., KEI Ind., Universal Cables, Techno Electric, as its listed peers. They are currently trading at a P/E of 58.0, 82.4, 21.3, 19.2, 52.6, 28.4, and 22.6 (as of Aug. 24, 2026). However, they are not truly comparable on an apple-to-apple basis. This comparison appears to be an eyewash.

Lumino Industries Ltd. (LIL) is a product-driven integrated engineering, procurement and construction (“EPC”) player in India, with strong focus on manufacturing (“Manufacturing”) and supplying conductors, power cables and electrical wires and other specialized products and components to the growing power transmission and distribution industry in India. The company also manufactures high-temperature low-sag (“HTLS”) conductors used in distribution and transmission lines in India. It achieved an Operating EBITDA Margin of 11.71% in Fiscal 2026. By leveraging its experience of more than three decades in the power transmission and distribution industry, the company has developed a product driven business model focused on designing, engineering, manufacturing and distributing specialized products used in a wide range of power transmission and distribution, industrial applications, electrical wiring, renewable energy projects, communication systems, electrical panels and railway networks applications.
LIL supplies conductors, power cables and other specialized products to large EPC players such as Kalpataru Projects International Limited (formerly known as Kalpataru Power Transmission Limited), Jackson Limited, Warora Kurnool Transmission Limited, K.G.N. Electricals, WRSS XXI (A) Transco Limited, Monte Carlo Limited and R.S. Infraprojects Private Limited. It also caters its products to international clients, which include government owned and controlled electricity companies, public enterprises and electricity boards, in countries such as United States of America, Mali, Burkina Faso, Côte d'Ivoire, Nepal, Bangladesh, Kenya, Ghana, Rwanda and Ethiopia. Further, in line with its product-driven strategy and integrated operations, the company also supplies products for captive consumption in the EPC projects executed by it. In Fiscal 2026, 23.08%2 of the specialised products used in the EPC projects were manufactured by LIL in-house.
Its integrated operations ensure captive consumption of a portion of its specialised products and reduces external dependence, driving consistency in demand and enhancing revenue stability. The captive consumption of its products helps the company in ensuring stable and predictable sales, while also streamlining production planning and reducing inventory risks. Similarly, by manufacturing critical products and components in-house, it has developed a reliable and uninterrupted supply chain for its EPC projects, reducing dependency on external vendors and mitigating risks associated with procurement delays or price volatility. The integrated operations enhance LIL’s project execution capabilities by allowing it to meet product specifications, while deriving cost efficiencies through economies of scale. Its distinct product driven business model improves its bidding capabilities for EPC projects (by minimizing external costs and maximizing operational flexibility) and enables it to improve receivable cycle and overall profitability.
LIL’s manufacturing facilities are a critical aspect of its integrated approach. This integration allows it to be more cost competitive and time efficient during the bidding process by leveraging its cross-feeding capabilities, resulting in economies of scale. The company operates two manufacturing facilities located in Howrah, West Bengal with a combined capacity of 40,000 metric tons (“MT”) of aluminium consumption per year for manufacturing cables and conductors, with an aggregate area of 264,208 sq. ft. It also operates four warehouses covering an aggregate area of approximately 156,600 sq. ft. Its manufacturing facilities are certified for ISO 9001:2015, ISO 14001:2015, ISO 45001:2018 and 5S Workplace Organizing Management Systems. The testing lab within its manufacturing facility for quality check of the finished products is accredited by the National Accreditation Board for Testing and Calibration Laboratories (“NABL”).
Its in-house manufacturing capabilities allows it to significantly reduce lead times and uncertainties associated with external suppliers, enabling faster response times. Further, its in-house manufacturing enhances inventory management by providing more accurate control over stock levels, reducing excess inventory and minimizing inventory shortages. As at March 31, 2026, it had 890 permanent employees. With an objective to establish a 250,000 sq. ft. manufacturing facility, it is in the process of expansion, for which the company has acquired approximately 650,000 sq. ft. of land in Ranihati, Howrah, West Bengal. This expansion will enable it to produce a wider range of cables and conductors like low voltage power cables, high voltage power cables, instrumentation cables, solar cables, railway signalling cable, flexible electrical wire, overhead aluminium conductors and HTLS conductors. LIL’s proposed manufacturing facility will help it in strengthening integration by increasing production capacity of overhead conductors, aerial bunch cables, and control cables used in electricity distribution and transmission, which will help it in creating greater synergy in manufacturing process.
The Company has received the Underwriter’s Laboratories (Global Safety Certification) Standards certification (“UL Certification”), demonstrating its ability to comply with the stringent safety and regulatory standards required by clients based in the U.S. and Europe, thereby significantly expanding its market opportunities in both the U.S. and European markets. UL certification is widely recognized as a mark of safety, quality, and compliance with industry standards, particularly in the U.S. and Europe, where regulatory requirements for product safety and performance are stringent. Its order book stood at Rs. 3149.88 cr. as of March 31, 2026.
Merchant Banker's Track Record
The three BRLMs associated with this offer have handled 73 issues in the last three years, out of which 23 issues closed below the issue price on listing date.
Conclusion
LIL is product driven integrated EPC player in India for power segment. It is marketing its products under LUMINO brand. As of March 31, 2026, it has an order book worth Rs. 3149.88 cr., indicating its near term prospects. The company marked progress in its top and bottom lines for the reported periods. Based on its recent financial average data, the issue appears reasonably priced. Well-informed investors can park funds for medium to long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.