Horizon Industrial Park IPO Review - Well-Informed/Cash Surplus Investors May Park Funds for Long Term
Horizon Industrial Park Ltd. (HIPL) is India’s largest industrial and logistics infrastructure developer, owner and operator in terms of Total Network (in terms of total area of our assets) (Source: JLL Report). It offers its clients Grade A quality fulfillment centers (warehouses), industrial facilities, and in-city centers across the country’s major industrial and consumption hubs. Its comprehensive business ecosystem provides a holistic end-to-end solution that enables its customers to operate seamlessly and reduce time-to-market. Its solutions include, among others, built-to-suit facilities, fully fitted plug-and-play facilities, cold storage, energy solutions, on-site staff accommodation, racking and material handling equipment (“MHEs”), all designed to support efficient operations. As of the date of this Red Herring Prospectus, its pan-India Network consists of 45 assets spread across 10 cities, totaling 58.58 million square feet (“msf”).
HIPL’s network of assets is spread across 10 major industrial and consumption hubs in India, including Delhi National Capital Region (“Delhi-NCR”), Mumbai (Maharashtra), Bangalore (Karnataka), Chennai (Tamil Nadu), Pune (Maharashtra), Hyderabad (Telangana), Ahmedabad (Gujarat) and Nagpur (Maharashtra). It has built this network through strategic acquisitions, greenfield developments that have transformed barren landscapes into thriving commercial hubs and targeted strategic redevelopments.
As of May 31, 2026, the company served a marquee customer base of over 118 customers, across key sectors of the Indian economy, including e-commerce, retail, fast-moving consumer goods (“FMCG”), renewable energy, auto-ancillary and manufacturing. Its scale, technical capabilities, network of strategically located sites and full-service offerings allow it to partner with both multinational corporations (“MNCs”) and domestic companies seeking to establish storage or manufacturing facilities in India. As of May 31, 2026, 54.05% of its committed Operational Network is contracted to Fortune 500 companies, which reflects the confidence that these global companies place in its capabilities and highlights the quality of customer base. Further, 40.65% of its incremental area contracted since Fiscal 2024 was signed through repeated engagements, underscoring customer stickiness and strengthening its customer relationships.
HIPL offers a fully integrated, end-to-end business ecosystem designed to address the comprehensive operational requirements of customers. It believes its business ecosystem facilitates seamless customer operations, fosters stickiness and supports the development of long-term relationships. Beyond retaining existing customers, its business ecosystem serves as a pull factor for potential clients. These offerings contribute directly to HIPL’s revenue streams.
As of the date of this Red Herring Prospectus, its pan-India Network consists of 45 assets spread across 10 cities, totaling 58.58 msf. As of May 31, 2026, its Operational Network spans across 28.55 msf, with a Committed Occupancy rate of 93.56%. The JLL Report forecasts continued acceleration in the market’s growth trajectory, with Grade A stock projected to expand at a 25.3% CAGR from CY2025 to CY2030, potentially reaching 943.6 msf by CY2030 (Source: JLL Report). As of the date of this Red Herring Prospectus, company’s Development Network is well-placed to capture this growth, with 30.03 msf of within-the-fence development, including 7.22 msf of Near Term Deliveries and 22.81 msf of Planned Projects expected to be delivered over the next four to five years. As of May 31, 2026, it had pre-contracted 2.57 msf to its customers across eight locations.
Over the last three fiscal years, its proforma revenue from operations has grown at a CAGR of 23.56%, and EBITDA margin, on a proforma basis, was 79.07% as of March 31, 2026. This combination is difficult to replicate, given its premium-quality offerings in prime markets, its proven execution capabilities and ability to acquire land at strategic locations and a skilled leadership team with industry experience. As of May 31, 2026, it had 268 employees on its payroll.
Promoters and Promoters Group
Mr. Urvish Rambhia: Chief Executive Officer (CEO) and Whole-Time Director
BREP Asia II EIP Holding (NQ) Pte.Ltd., Brep ASIA II Indian Holdings Co.VI (NQ) Pte.Ltd. and BREP Asia III India Holdings Co.III Pte.Ltd.: Promoter and Wholetime Director
Issue Details / Capital History
The company is coming out with its maiden book building route IPO worth Rs. 2600 cr. (approx. 433333333 equity shares at the upper cap). The company has announced a price band of Rs. 57 – Rs. 60 per equity shares of Rs. 10 each. The issue opens for subscription on August 17, 2026, and will close on August 19, 2026. The minimum application to be made is for 250 shares and in multiples thereon, thereafter. Post allotment, shares will be listed on BSE and NSE. The issue constitutes 15.03% of the post-IPO paid-up equity capital. From the net proceeds of the fresh equity issue, the company will utilize Rs. 2250.00 cr. for repayment/prepayment of certain borrowings, and the rest for general corporate purposes.
The company has reserved equity shares worth Rs. 5.00 cr. (approx. 833333 equity shares at the upper cap), and offering them a discount of Rs. 5.00 per share. From the rest, it has allocated not less than 75% for QIBs, not more than 15% for HNIs and not more than 10% for Retail investors.
The five Book Running Lead Managers (BRLMs) to this issue are JM Financial Ltd., Axis Capital Ltd., IIFL Capital Services Ltd., SBI Capital Markets Ltd., and 360 ONEWAM Ltd., while KFin Technologies Ltd. is the registrar to the issue. JM Financial Services Ltd., Investec Capital Services (India) Pvt. Ltd., SBICAP Securities Ltd., 360 ONE Capital Market Pvt. Ltd., 360 ONE Distribution Services Ltd. are the syndicate members.
After issuing initial equity shares at par value, the company has issued/converted further equity shares in the price range of Rs. 15.00 - Rs. 59.81 between March 2018, and December 2025. The average cost of acquisition of shares by the promoters/selling stakeholders is Rs. 22.39, Rs. 28.20, and Rs. 29.94 per share.
Post-IPO, its current paid-up equity capital of Rs. 2449.53 cr. will stand enhanced to Rs. 2882.86 cr. Based on the upper cap of the price band, the company is looking for a market cap of Rs. 17297.16 cr.
IPO Lead Managers & Registrar
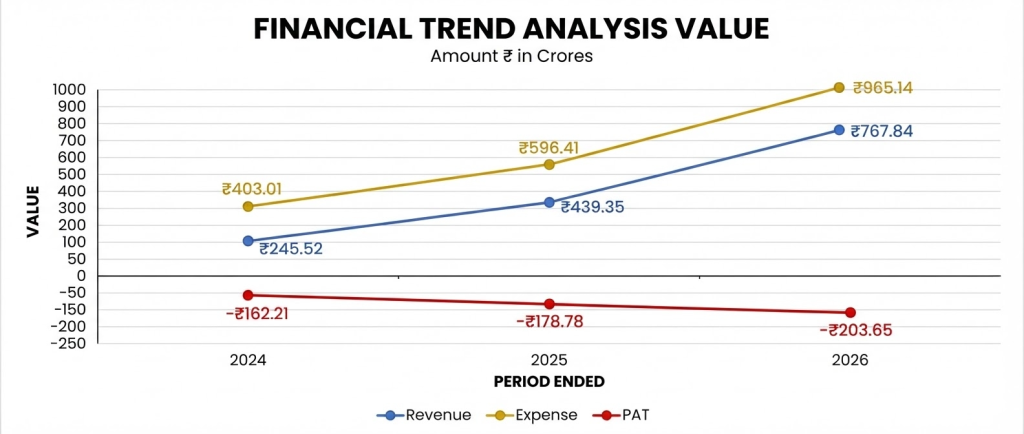
On the financial performance front, for the last three fiscals, the company has (on a consolidated basis) posted a total income/net profit/ - (loss), of Rs. 245.52 cr. / Rs. – (162.21) cr. (FY24), Rs. 439.35 cr. / Rs. – (178.78) cr. (FY25), and Rs. 767.84 cr. / Rs. – (203.65) cr. (FY26). The company posted growth in its top lines but bottom line remained in red for the reported periods. Losses for the last three fiscals at net level has resulted in a negative P/E.
On Proforma basis, it has posted a total income/net profit/ - (loss) of Rs. 475.98 cr. / Rs. – (275.07) cr. (FY24), Rs. 644.78 cr. / Rs. – (239.43) cr. (FY25), Rs. 765.16 cr. / Rs. – (190.82) cr. Here also it has posted losses for al the three years. Its contingent liability stood at Rs. 50.38 cr. as of March 31, 2026.
According to the management, it is operating in a specialized segment for industrial park realty and enjoys niche place with cream list of clients having long term contracts. The company is expanding its capacity to more than double in next three years and with its plans for repayment of debt will make it debt free at one hand, and its bottom line will improve drastically with the finance cost saving.
For the last three fiscals, the company has posted an average EPS of Rs. – (2.12) (On restated basis) and an average RoNW of – (57.47) %. The issue is priced at a P/BV of 2.15 based on its NAV of Rs. 27.89 (on restated basis) as of March 31, 2026, and at a P/BV of 1.74 based on its post-IPO NAV of Rs. 34.49 per share (on restated basis) at the upper cap.
As the company has posted losses for the reported periods, its IPO is being offered at a negative P/E. Its positive NAV is simply on account of equity issue is done at premiums. For the reported periods, the company has posted losses and hence has not shown data for its PAT and RoCE margins. But as presented in the offer document, it has posted EBITDA margins (on a restated basis) of 61.71% (FY24), 77.19% (FY25), 79.16% (FY26).
All amounts in Indian Rupees crores
The company has not paid any dividends for the reported periods of the document. It has already adopted a dividend policy in December 2025, based on its financial performance and future prospects.
Comparison with Listed Peers
As per the offer document, the company has no listed peers to compare with. (As per remarks in the offer document - As of the date of this Red Herring Prospectus, its pan-India Network consists of 45 assets spread across 10 cities, totalling 58.58 million square feet (“msf”). There are no companies which have their equity shares listed in India and in other major select economies, which operate purely as an industrial and logistics park developer, and are comparable with HIPL’s business model, according to the JLL Report. Accordingly, it is not possible to provide an industry comparison in relation to the Company. This absence of directly comparable publicly available information may affect investors’ ability to assess its relative performance and industry position)
Merchant Banker's Track Record
The five BRLMs associated with this issue has handled 110 IPOs in the last three fiscals out of which 31 issues closed below the issue price on the listing date.
Conclusion
HIPL is India’s largest industrial and logistics infrastructure developer serving many marquee customers. It posted consistent growth in its top lines, but due to capex made so far, its financial adjustments resulted in losses at the net level. The company has up the sleeve plans for doubling of its offerings. Due to losses for its financial performance for the last three fiscals, the IPO is at a negative P/E. Blackstone’s holding around 75% post IPO augurs well. Considering its development plans, it’s a pure long term story. Well-informed/cash surplus investors may park funds for long term.
Dilip Davda is a veteran financial journalist associated with the Indian stock market since 1978. He has been contributing to print and electronic media on capital markets, insurance, and finance since 1985.
He is widely recognized for reviewing public issues and non-convertible debentures (NCDs) in the primary market. Drawing on over three decades of market experience and close interaction with merchant bankers, his reviews focus on detailed fundamental and financial analysis of companies, with a special emphasis on SME public issues.
Disclaimer: The information provided herein is solely for educational and informational purposes and does not constitute an offer, solicitation, or recommendation to buy or sell any securities. Readers are advised to consult a qualified financial advisor before making any investment decisions. Investments in the securities market are subject to market risks. The author does not intend to invest in the securities discussed.